A trusted business law firm in McKinney, TX.

Business Law

Business Law

The proposed 2026 “Dynastic Wealth” Bill

The 2026 “Dynastic Wealth” Bill:

Why Estates Between 3.5 and 15 Million Are Squarely in the Crosshairs of this Proposed Legislation

In March 2026, Democratic Senator Chris Van Hollen introduced S. 4196, the Strengthen Social Security by Taxing Dynastic Wealth Act, a proposal that would dramatically reset federal estate and gift taxes starting in 2027. While the bill is often described as targeting “ultra‑wealthy” families, the most immediate impact would fall on estates in roughly the 3.5–15 million per‑person range; families who are affluent but not necessarily thinking of themselves as “dynastic.” Estate Planning Attorney, Mr. Mike Weaver
For these households, the key planning question is not just what the bill does, but when. The timing of the proposed changes creates a powerful, but time‑limited, opportunity to act before the end of 2026.

Where We Are Today: Historically High Exemptions Through 2026

Under current law, the lifetime federal estate and gift tax exemption for 2026 is projected to be about 15 million per person, or 30 million for a married couple, with a top transfer‑tax rate of 40%. That means many well-off families, especially those with estates between 3.5 and 15 million per person, are outside the reach of federal estate tax entirely.

These historically high exemption levels are scheduled to stay in place through December 31, 2026, under current law. For planning purposes, this gives clients one more year where very large lifetime gifts can be made without triggering federal transfer tax, so long as those transfers are completed before year‑end 2026.

What S. 4196 Would Do Starting in 2027

S. 4196 would essentially turn the clock back to the 2009 transfer‑tax regime and redirect the resulting revenue into Social Security. The core changes are straightforward but severe for upper‑middle‑market estates.

  • Estate tax exemption reset: The federal estate tax exclusion would drop to 3.5 million per individual (7 million for a married couple), with a top rate of 45%.
  • Gift tax decoupled and capped: The unified structure would be broken; lifetime gifts would receive only a 1 million exemption for gift‑tax credit purposes.
  • Effective date: These new rules would apply to estates of decedents dying and gifts made after December 31, 2026.

For families with net worth between roughly 3.5 and 15 million per person, the difference is dramatic: an estate that today would pass free of federal tax could face a sizable 45% estate tax on amounts exceeding the new 3.5 million threshold if S. 4196 becomes law.

The “Use It or Lose It” Window: Why 2026 Is Critical

One of the most important features of S. 4196 is what it does not do: it does not claw back valid large gifts made in 2026 under today’s elevated exemption. Large lifetime transfers completed before January 1, 2027 can still use the current 15 million per‑person unified credit, even though future gifts would be capped at 1 million.

In practice, this sets up a two‑stage planning framework:

  • Stage 1 – Before December 31, 2026:
    Families can make substantial gifts, often into irrevocable trusts, using the current high exemption, removing future appreciation from their taxable estates while incurring no immediate transfer tax.
  • Stage 2 – After December 31, 2026:
    Assuming S. 4196 or a similar regime is in effect, only a 1 million lifetime gift exemption remains for fine‑tuning, not for large transfers. At death, everything above the 3.5 million estate exemption per person is exposed to estate tax at rates up to 45%.

For an estate in the 10 million range, the difference between fully using the 2026 exemption versus doing nothing could be measured in millions of dollars of estate tax under the proposed rules.

Why the 3.5–15 Million Range Is So Exposed

Families above about 15 million per person are already planning around federal estate tax and typically have sophisticated structures in place. By contrast, households in the 3.5–15 million band often assume they will stay below any realistic federal estate‑tax threshold and may not have done extensive transfer‑tax planning.

S. 4196 changes that calculus overnight:

    • Estates between 3.5 and 15 million per person, which are untaxed today, become fully taxable above the 3.5 million mark.
    • Closely held business interests, operating companies, ranches, and real estate portfolios that were never modeled for federal estate tax could suddenly need liquidity solutions to pay a 45% tax on value above the exemption.
    • Because the proposal dedicates all estate, gift, and generation‑skipping transfer tax revenue to a unified Social Security Trust Fund, those taxes may become politically harder to roll back in the future.

In other words, this is the group most likely to be caught by surprise, unless they make proactive use of the 2026 planning window.

The New Gifting Landscape After 2026

The shift from a 15 million unified exemption to a 1 million lifetime gift cap fundamentally changes how gifting will work if S. 4196 passes.

Under today’s rules, a client can gradually or in one stroke shift tens of millions of dollars out of the taxable estate using the unified credit, relying on techniques like spousal lifetime access trusts (SLATs), dynasty trusts, and transfers of discounted entity interests. After 2026, the gift exemption would mainly serve as a tool for incremental clean‑up transfers, not for major wealth shifts.

That makes 2026 the decisive year for clients who want to:

  • Move high‑growth assets, such as operating businesses, ranch or mineral interests, or concentrated equity positions, out of the taxable estate while values are still within the current high exemption; and
  • Lock in today’s rules before the combination of a 3.5 million estate cap and a 1 million gift cap sharply limits what can be done later without incurring tax.

Advisors are already encouraging clients to treat 2026 as a rare “last call” moment for large‑scale lifetime planning.

What To Do Now

S. 4196 is still proposed legislation and may change, but it reflects a clear policy direction: lower exemptions, higher transfer‑tax burdens, and a tighter link between those taxes and Social Security funding. For families in the 3.5–15 million per‑person range, ignoring that direction could be costly.

Practical next steps include:

  • Updating personal balance sheets and entity diagrams to understand current net worth and trajectory.
  • Modeling estate‑tax exposure under both today’s rules and a 3.5 million / 45% S. 4196 regime.
  • Identifying high‑appreciation assets that are strong candidates for 2026 lifetime gifts.
  • Coordinating with legal, tax, and financial advisors to implement a gifting plan well before December 31, 2026.
Michael A. WeaverThe window is open now, but if S. 4196 moves forward and becomes law, that window closes at midnight on December 31, 2026.

While this proposed law may or may not become final, don’t wait to build appropriate estate planning, trust, and gifting strategies for your family. It’s essential to consult with an experienced estate planning attorney to determine the best approach for your specific circumstances and ensure your estate planning documents are properly prepared and legally sound. Mr. Michael A. Weaver, Partner at Saunders | Walsh, specializes in estate planning law and looks forward to working with your family to protect your legacy assets. Call us today to schedule your consultation with Mr. Weaver.
Read more

The Office of Strategic Capital: A New Financing Tool for Critical Technology Companies

The Office of Strategic Capital: A New Financing Tool for Critical Technology Companies

The U.S. Department of Defense has created a financing office that deserves attention from companies, investors, and advisors working in defense-adjacent technology: the Office of Strategic Capital, or OSC. OSC was established to attract and scale private capital into technologies and supply chains that are important to U.S. national security (OSC About).

Unlike a traditional procurement office, OSC is not simply buying goods or services for the government. Its role is to use financial tools, including loans and loan guarantees, to help critical technology companies scale production capacity (FY2025 Investment Strategy).

Why OSC Matters

Many critical technologies need large amounts of capital before they can reach commercial scale. That can include manufacturing equipment, production facilities, supply-chain expansion, or modernization of existing assets.

OSC is designed to address that gap by using the strength of U.S. capital markets to “crowd in” private investment for national-security priorities (OSC About). Congress gave OSC statutory authority through the FY2024 National Defense Authorization Act, including authority to provide loans, loan guarantees, and technical assistance in covered technology categories (FY2025 Investment Strategy).

The Equipment Finance Program

OSC’s first major direct lending product is an equipment finance program. The initial program made up to $984 million available for direct loans to finance the construction, expansion, or modernization of commercial equipment in the United States (Federal Register Notice).

Loan sizes under that first offering ranged from $10 million to $150 million (Federal Register Notice). OSC states that its credit program may offer Treasury-rate-based pricing, longer repayment periods, deferred payment, flexible amortization, and the ability to combine OSC loans with private equity, corporate debt, grants, and other sources of funding (OSC Credit Program).

Covered Technologies

OSC’s covered technology categories include advanced manufacturing, microelectronics, battery storage, cybersecurity, edge computing, quantum computing, quantum security, quantum sensing, space launch, spacecraft, synthetic biology, and advanced materials (FY2025 Investment Strategy). OSC’s FY2025 strategy also identified particular interest in areas such as autonomous mobile robots, hydrogen generation and storage, microelectronics assembly, microelectronics manufacturing equipment, sensor hardware, spacecraft, and synthetic biology (FY2025 Investment Strategy).

Who May Be a Fit

OSC financing is not aimed at every startup. The credit program is generally focused on creditworthy businesses that can show project viability and repayment capacity (OSC Credit Program).

U.S.-domiciled public and private companies may be eligible, including companies with foreign ownership, if they support a covered technology category and meet program requirements (OSC Credit Program). OSC states that early-stage, pre-revenue companies are generally not eligible unless supported by a repayment guarantee from a creditworthy sponsor (OSC Credit Program).

Projects may also face issues if the federal government is the sole expected user, if repayment depends mainly on federal grants or contracts, or if counterparties or project jurisdictions raise U.S. national-security concerns (OSC Credit Program).

A Strong Demand Signal

Demand for OSC financing appears significant. OSC reported more than 200 applications totaling $8.9 billion in financing requests for its first domestic manufacturing loan program, compared with $984 million in initial lending capacity (DoD Release).

That demand suggests companies are actively looking for alternatives to traditional commercial debt, venture capital, and government procurement. For capital-intensive businesses in critical technology sectors, OSC may become an important part of the financing landscape.

Key Takeaways

Companies considering OSC financing should evaluate whether their project fits a covered technology category, whether the project has a strong domestic manufacturing or supply-chain nexus, and whether the company can demonstrate repayment capacity. Counsel and advisors should also consider foreign ownership, national-security risk, federal funding dependence, and federal compliance requirements such as NEPA, Davis-Bacon, American Iron and Steel, and Build America Buy America (OSC Credit Program).

The bottom line is that OSC is not a grant program and it is not ordinary defense procurement. It is a strategic credit platform designed to help private companies scale technologies and supply chains that matter to U.S. national security.

For businesses in advanced manufacturing, microelectronics, energy storage, space technology, quantum, robotics, and other covered sectors, OSC is worth watching closely.

If you are considering designing a plan for OSC financing as part of your growth strategy, consult with a Texas corporate attorney like Michael A. Weaver at Saunders | Walsh to ensure corporate compliance and structural efficiency.

Read more

Funding Buy-Sell Agreements with Life Insurance After Connelly v. United States

Funding Buy-Sell Agreements with Life Insurance
After Connelly v. United States

Funding Buy-Sell Agreements with Life InsuranceFor closely held businesses, a well-drafted, properly funded buy-sell agreement is one of the most important—and most frequently mishandled—estate planning tools. A buy-sell sets the rules of engagement for what happens to an owner’s interest at death, disability, or departure and, when paired with life insurance, can provide the liquidity needed to keep the business and the family both financially secure.
But the Supreme Court’s decision in Connelly v. United States is a stark reminder that how you structure and fund that agreement can dramatically change the estate tax result. A buy-sell that looks fine from a corporate or succession-planning perspective can actually increase the taxable estate if the insurance and ownership mechanics are not carefully aligned with the valuation rules of the Internal Revenue Code.

Why Life Insurance Is the Workhorse Funding Vehicle

Most owners like the concept of a buy-sell agreement in theory. The friction usually arises around the question: “Where does the money come from to actually buy the deceased owner’s interest?”

Life insurance solves that problem elegantly:

      • It creates immediate, liquid cash at the exact time it is needed; upon an owner’s death.
      • It avoids forcing the company or the surviving owners to borrow on unfavorable terms or fire-sale assets just to complete the buyout.
      • It converts an illiquid business interest into cash for the deceased owner’s family, which is often far more useful for a surviving spouse or heirs who are not involved in the business.

In short, insurance is not the agreement; it is the funding engine that allows the agreement to work under real-world stress. The legal and tax consequences, however, depend critically on who owns the policy, who is the beneficiary, and how the buy-sell is drafted.

Common Structures: Cross-Purchase vs. Entity Redemption

Although there are hybrids and variations, most life-insurance-funded buy-sell plans fall into one of two basic models: cross-purchase or entity redemption (entity purchase). Each has distinct ownership, tax, and administrative implications.

Cross-Purchase Structure

Under a cross-purchase arrangement:

      • Each owner buys and owns a policy on the life of the other owner(s).
      • When an owner dies, the surviving owner(s) collect the death benefit personally and use it to purchase the deceased owner’s shares under the buy-sell agreement.
      • The surviving owners receive a basis step-up in the shares they purchased, which can be valuable if the business is later sold.

Advantages:

    • The insurance proceeds never sit inside the company itself, so they generally are not building the value of the corporation for estate tax purposes.
    • Surviving owners individually acquire more stock with a higher basis, which may reduce future capital gains on a sale.

Challenges:

      • With more than a few owners, the number of policies required can become unwieldy (each owner needs policies on each of the others).
      • Premiums may not be perfectly “equal” if there are big age or health differences among owners.

Entity Redemption Structure

Under an entity redemption:

      • The company owns policies on each owner’s life and is the beneficiary of those policies.
      • When an owner dies, the company receives the death benefit and uses those funds to redeem (buy back) the deceased owner’s shares under the buy-sell agreement.
      • The remaining owners’ percentage interests increase, but their tax basis in their shares does not.

Advantages:

      • Administrative simplicity: the entity owns one policy per owner, pays the premiums, and handles any changes centrally.
      • Often easier to explain and implement for larger ownership groups.

Risks:

      • Because the insurance proceeds are received by the entity, they increase the value of the company itself, which becomes a central issue for estate tax valuation.
      • If the agreement is not drafted and operated within the strict requirements of the valuation rules, the tax results can be far worse than expected.

The Connelly decision squarely focused on this entity-redemption model.

The Connelly Case: When the Insurance Creates the Tax Problem

In Connelly v. United States, the Supreme Court reviewed an estate tax dispute arising from a family-owned corporation that used a redemption-style buy-sell agreement funded with corporate-owned life insurance. The key facts, simplified:

      • The corporation owned a life insurance policy on a shareholder’s life and was the beneficiary.
      • The buy-sell agreement provided that on a shareholder’s death, the corporation would redeem the deceased shareholder’s stock using the insurance proceeds.
      • For estate tax purposes, the estate argued that the corporate-owned life insurance should effectively be ignored or offset by the corresponding obligation to redeem the shares; i.e., that the insurance did not increase the value of the corporation for valuation purposes.

The Supreme Court rejected that argument. The Court held that:

    1. The life insurance proceeds received by the corporation are a valuable corporate asset that must be included in the fair market value of the company when determining the value of the decedent’s stock for estate tax purposes.
    2. The corporation’s contractual obligation to redeem the decedent’s shares does not reduce the value of the corporation in that valuation exercise. A redemption obligation is essentially an arrangement among shareholders, not a corporate liability that diminishes enterprise value in the eyes of a hypothetical willing buyer.

The result was harsh: the insurance increased the company’s value for estate tax purposes, thereby increasing the value of the decedent’s shares, even though those same insurance dollars were earmarked to redeem those shares. The estate ended up paying estate tax on a higher value while the actual economic benefit to the family did not increase proportionately.

In addition, the Court and the IRS looked closely at the buy-sell agreement itself. The agreement failed to meet the requirements under Internal Revenue Code Section 2703 for an agreement to control value for estate tax purposes:

      • The agreement did not operate as a true, binding arm’s-length arrangement;
      • It was not consistently observed in practice; and
      • It did not provide a fixed or formula-based price that would be respected for valuation purposes.

Because the agreement was not respected as a bona fide price-setting mechanism, the IRS and the Court fell back to general fair market value principles, which included the insurance proceeds at full value.

The Estate Tax Risk of “Wrong” Structure

The lesson from Connelly is not that entity-redemption agreements are dead, but that they are dangerous if you assume the life insurance funding will be tax neutral at the corporate level.

The core estate tax risks include:

      • Inflated Estate Value: When the corporation owns the policies, the death proceeds can significantly increase the company’s value at the moment of death, directly increasing the decedent’s taxable estate.
      • No Offset for Redemption Obligation: A contractual requirement for the company to redeem shares using those same proceeds typically will not reduce the corporate value for estate tax purposes. The estate may feel like the insurance “just passes through,” but for valuation purposes it is effectively an asset that boosts the company’s worth.
      • Unrespected Buy-Sell Price: If the agreement’s price mechanism is not carefully drafted, regularly updated, and actually followed, the IRS may disregard the stated price and instead use a higher fair market value, including the insurance.
      • Mismatch Between Economic and Tax Outcomes: The family may end up with the same economic result they always expected (cash for shares, surviving owners with 100% of the company), but with a significantly larger estate tax bill, reducing the net value transferred to heirs.

For closely held businesses where the business interest is the primary asset in the estate, that mismatch can be catastrophic.

Drafting and Structuring After Connelly: Practical Guidelines

Attorneys and advisors can still use life insurance to fund buy-sell agreements effectively, but the post-Connelly environment calls for more precision in structure and documentation.

    1. Be Intentional About Policy Ownership

Consider whether corporate ownership of the policies is truly necessary, or whether a cross-purchase or alternative structure (such as a separate LLC or trust to own policies) can achieve the same funding benefits with less estate tax exposure.

      • For two or three owners, a traditional cross-purchase is often manageable and may keep the insurance proceeds out of the entity’s value.
      • For larger groups, look at techniques that centralize policy ownership outside the operating company rather than inside it.
    1. Tighten the Buy-Sell Agreement Under Section 2703

If you want the buy-sell to influence or control the value used for estate tax purposes, it must be drafted to meet the statutory and regulatory requirements:

      • Use a clear, objective price mechanism (such as a regularly updated formula tied to earnings, EBITDA multiples, or independent appraisals) rather than vague or ignored valuation language.
      • Require periodic updates to the stated value or formula and document those updates; then actually transact at those values when triggering events occur.
      • Ensure the agreement is binding on the parties both during life and at death, and that it resembles an arm’s-length arrangement rather than a device to artificially depress estate values.
    1. Coordinate Insurance, Valuation, and Corporate Records

The buy-sell agreement, the insurance policies, and the corporate records (minutes, cap table, financial statements) must tell a consistent story:

      • Confirm that policy ownership and beneficiary designations match the structure described in the buy-sell.
      • Ensure that financial statements properly reflect corporate-owned policies and that appraisers understand the treatment of those policies under current law.
      • Revisit both the agreement and coverage amounts as the business value changes; an outdated policy or stale valuation can be as dangerous as no planning at all.
    1. Model the Estate Tax Outcomes in Advance

For key owners, it is prudent to model:

      • The projected value of the business with and without insurance proceeds at death.
      • The resulting estate tax liability under different structures (cross-purchase vs. entity redemption vs. external policy-owning entities).
      • The net amounts expected to pass to family members after tax under each approach.

These projections help owners understand that “simpler” is not always safer and that the short-term convenience of entity-owned policies may carry long-term estate tax cost.

Takeaways for Business Owners and Advisors

Life-insurance-funded buy-sell agreements remain a powerful way to combine business succession and estate planning. They provide liquidity when it is needed most and can prevent families from being forced into bad deals or litigation in the wake of an owner’s death.

The Connelly decision, however, is a reminder that the tax law does not always align with intuitive economics. When the entity owns the life insurance and is the beneficiary, those proceeds may increase the value of the decedent’s stock for estate tax purposes, even if they are immediately used to redeem that stock under a buy-sell agreement. If the agreement itself is not drafted and operated to meet strict valuation requirements, the IRS and the courts may ignore the nominal “buy-sell price” and impose tax on a significantly higher value.

For that reason, buy-sell agreements should be reviewed not only through a corporate or transactional lens, but through an estate tax lens. Aligning the structure (cross-purchase vs. entity redemption vs. alternative ownership vehicles), the insurance funding, and the valuation mechanics is essential to avoid turning what was intended as a tax-efficient succession plan into an estate tax trap.

Michael A. WeaverIf you have an existing buy-sell agreement funded with life insurance—especially if the corporation owns the policies—this is an excellent time to have it reviewed in light of Connelly and to confirm that the structure will produce the estate tax result you actually intend. Mr. Michael A. Weaver, Partner at Saunders | Walsh, specializes in estate planning and corporate law and looks forward to working with you to build buy-sell provisions in your Company Agreement that work. Call us today to schedule your consultation with Mr. Weaver.

Read more

What Your Insurance Agent Needs to Know When a Living Trust Owns a Texas Series LLC

What Your Insurance Agent Really Needs to Know When a Living Trust Owns a Texas Series LLC

When a Living Trust Owns a Texas Series LLC:

What Your Insurance Agent Really Needs to Know


When you combine a living trust, a Texas series LLC, and multiple lines of business insurance, you create a structure that is great for asset protection but confusing for insurance underwriting. This post walks through the key issues that come up when an insurance agent calls to “understand the disregarded entity tax structure” and how you, as counsel or advisor, can be ready with clear, consistent answers.

  1. Who Really Owns and Controls the Business?

The first thing a business‑insurance agent wants to nail down is: who is the insured risk?

In a typical planning structure:

  • The revocable living trust is the sole member of the parent LLC.
  • That parent LLC establishes multiple series, each holding a specific asset pool or business line (for example, separate rental properties or operating ventures).
  • The trustee—often the grantor—is the manager of the LLC and its series.

From an insurance standpoint, the key is to make sure:

  • The parent LLC and the relevant series appear as named insureds or scheduled entities on the policy.
  • The trust and the individual trustee/grantor appear as additional insureds (or co‑named insureds where possible).

This alignment reduces the risk that a claim is denied because the “real party” with liability or ownership was never properly named on the policy.

  1. Disregarded Entities: Tax Fiction vs. Insurance Reality

For federal tax purposes, single‑member LLCs (including those owned by a grantor trust) are routinely treated as disregarded entities. In practice, that means:

  • Each series’ income flows through the trust and onto the grantor’s Form 1040.
  • The IRS looks through the LLC and trust and taxes the grantor directly.

Insurance carriers, however, do not underwrite tax fictions. They care about:

  • Which legal entity holds title to the property or employs people.
  • Where operations occur and who signs contracts and leases.
  • Whose financial statements (often the grantor’s return plus entity‑level books) reflect the risk they are insuring.

The smart move is to explain to the agent that the tax treatment doesn’t change who owns assets or runs the business; it simply affects how income is reported. Then offer:

  • EINs for each series and the parent LLC.
  • A short explanation of how the grantor trust and disregarded entities report on the individual return.

This lets underwriting connect the dots between entity‑level exposures and the individual’s tax return they’ll often see in underwriting.

  1. How Texas Series LLCs Affect Coverage Design

Texas series LLCs are popular for real estate and multi‑asset businesses because each series can hold its own assets and liabilities while sitting under a single umbrella LLC. For insurance, this raises several design questions:

  • Should each series be treated as a separate “location” under one master policy, or as separate insured entities?
  • Should there be one combined program (with clear scheduling of each series) or separate policies for each series?
  • How should limits and umbrellas be structured to respect internal liability segregation while still providing practical coverage?

A common, practical approach:

  • Use one coordinated program, with the parent LLC and each active series listed by name.
  • Clearly schedule properties and operations under the correct series on the declarations and schedules.
  • If certain series have meaningfully different risk profiles (e.g., high‑risk operations vs. passive real estate), consider separate policies or endorsements to avoid cross‑subsidization of risk.

The better you document which series owns what, the easier it is for the agent to avoid gaps.

  1. Trust Ownership: Why It Matters to the Carrier

Trust ownership introduces two issues carriers care about: control and continuity.

With a revocable living trust:

  • The grantor and the trust are economically the same person during the grantor’s life.
  • However, the trust instrument governs what happens on incapacity or death—when a successor trustee steps in, and how business interests transition.

Insurance implications include:

  • Ensuring the trust itself is recognized on the policy, so coverage continues seamlessly even if the grantor dies or becomes incapacitated.
  • Ensuring the trustee (and any successor trustee) is recognized as having authority to act for the insured entities.
  • Clarifying that any change in trusteeship or substantial amendment to the trust will trigger notice to the agent so the carrier can update the policy if needed.

When you proactively share a high‑level summary of the trust’s role—without revealing unnecessary private details—you reduce carrier anxiety about “mystery owners” behind the scenes.

  1. Business Income, Payroll, and “Who Is the Employer?”

When agents ask about “the disregarded entity tax structure,” they are often really asking about:

  • Whose income is at risk for business‑income and extra‑expense coverage.
  • Who is the employer for workers’ comp, employment‑practices, and related coverages.

In a common arrangement:

  • The payroll for each line of business runs through the specific series’ EIN, even though the series is disregarded for income‑tax purposes.
  • The books and records track revenue, expenses, and payroll by series, then roll up through the parent LLC and ultimately to the grantor’s return.

For underwriting clarity, it helps to be ready with:

  • Current payroll reports by entity/series.
  • A brief explanation of where business‑income coverage should respond (e.g., at the series level, based on its own revenue).
  • Confirmation that the tax “flow‑through” does not change which entity is responsible for payroll taxes and employment obligations.

This makes it easier to size limits and price the policy correctly.

  1. Documentation and Communication Best Practices

To make these calls productive and avoid follow‑up confusion, it’s worth investing in a simple documentation package:

  • A one‑page structure diagram showing the trust, the parent LLC, and each series with a short label (e.g., “Series A – Elm St. Rental,” “Series B – Equipment Leasing”).
  • A brief written summary (1–2 paragraphs) explaining:
    • That the trust is a revocable grantor trust.
    • That each series is a single‑member LLC owned by the trust and treated as a disregarded entity.
    • That all income flows to the grantor’s Form 1040, but assets and operations are legally held at the entity/series level.
  • A list of requested policy positions, such as:
    • Parent LLC and each series as named insureds or scheduled entities.
    • Trust and trustee as additional insureds.
    • Agreement to notify the agent on changes to trustees, series, or major operations.

Having this ready before the call lets you answer the agent’s questions consistently and gives the underwriter something concrete to work from.

  1. How to Talk About “Disregarded” Without Losing the Agent

Finally, remember that “disregarded entity” is tax jargon. In conversations with agents:

  • Emphasize that for legal liability, each LLC series still exists and owns assets or runs operations.
  • Clarify that for tax reporting, those entities are ignored and everything flows to the individual grantor’s return.
  • Tie every explanation back to what the carrier cares about: who owns the property, who operates the business, who employs people, and whose financials demonstrate the risk.

If you keep the focus on legal ownership, operations, and claims exposure, the tax‑classification piece becomes a simple background detail rather than a point of confusion.

Michael A. Weaver


Prepare Your Documentation Package Today

Don’t wait for the call from the underwriter. Proactively assemble the documentation package described in Section 6—including your structure diagram, high-level trust summary, and desired policy positions—to ensure a smooth, confusion-free underwriting process and avoid gaps in coverage. Need help? Contact Mr. Mike Weaver, Partner at Saunders | Walsh, today.  

Read more

What Every Commercial Tenant Should Know Before Signing a Lease in Texas

Avoid costly mistakes by understanding the fine print of your lease agreement.

Signing a commercial lease in Texas is a major business decision, and one that can impact your bottom line for years to come. Unlike residential leases, commercial leases in Texas are largely unregulated and highly customizable, which means tenants must be vigilant.

At Saunders, Walsh & Beard, we regularly help business owners navigate complex lease agreements. Here are some of the most important issues every tenant should understand before committing:

  1. Lease Type Matters More Than You Think
    Is it a gross lease, net lease, or triple net (NNN) lease? In NNN leases, which are common in Texas, tenants are often responsible for taxes, insurance, and property maintenance. Understanding the financial structure can help you avoid unexpected costs.
  1. Who’s Responsible for Repairs?
    Many Texas leases shift the burden of HVAC, roof, and even structural repairs onto the tenant. Always clarify responsibilities and consider negotiating a cap on major repair costs.
  1. Renewals and Early Termination
    Watch for automatic renewal clauses and rigid termination terms. If your business outgrows the space or operations stall, these clauses can trap you.
  1. Escalating Rent and CAM Charges
    Leases often include annual rent increases and Common Area Maintenance (CAM) fees. Ask for historic

    What to know before signing a commercial lease.

    al expense reports and consider negotiating audit rights and limits on increases.

  1. Use Restrictions
    A narrow use clause can prevent you from expanding services or subleasing. Request broader language that accommodates your current and future business operations.
  1. Assignment, Subleasing, and Exit Strategy
    Without the right language, landlords can block a transfer or keep you liable after you exit. Protect yourself by negotiating assignment rights and liability releases.
  1. Lockouts and Landlord Remedies
    Texas law permits commercial lockouts if rent isn’t paid. Ensure your lease includes notice and cure periods to avoid abrupt business interruptions.
  1. Personal Guaranties
    If you’re signing on behalf of an LLC or corporation, the landlord may still ask for a personal guaranty. Limit its duration and scope whenever possible.
  1. Dispute Resolution and Venue
    Arbitration clauses and far-away court venues can work against you. Aim for local venue provisions and consider requiring mediation before litigation.
  1. Improvements and Build-Outs
    Know whether you’re allowed to modify the space, and whether you’ll need to remove improvements when you leave. Ask about tenant improvement (TI) allowances upfront.
  1. Insurance and Liability
    Ensure your insurance obligations are reasonable and request a waiver of subrogation to protect against third-party claims.
  1. Force Majeure and Shutdowns
    After COVID-19, many landlords now exclude pandemic-related rent relief. Negotiate protections for future business interruptions.


Final Word: Protect Yourself Before You Sign
Texas is a landlord-friendly state. That’s why it’s essential to have a knowledgeable attorney review (and if necessary, negotiate) your lease before signing. At Saunders, Walsh & Beard, we’re here to ensure your lease works for your business, not against it.

Need help with a lease? Contact us today to schedule a consultation with a commercial real estate attorney.

Read more

The Benefits of Trademark Protection

The Benefits of Trademark Protection

When building your business, one of the most important assets you have is the brand itself. Whether it’s the name of your company, a slogan or a logo, finding distinct ways to represent your company will help build consumer awareness, enabling your business to grow. Filing a trademark with the United States Patent and Trademark Office (USPTO) offers significant benefits for protecting and growing your brand.

  • Exclusive U.S. Rights: When you file for a trademark, you will be granted exclusive rights to use the trademark in connection with your goods or services across the U.S., regardless of where you’re physically located. Additionally, it helps prevent others from using a confusingly similar name or logo.
  • Stop Copycats: Once you file with the USPTO, your mark becomes publicly searchable in the USPTO database. This deters others from adopting a similar name or logo because they can see it’s already claimed.
  • Public Deterrent: Registered marks are presumed valid, and you are presumed to be the rightful owner, thereby shifting the burden of proof to the other party in legal disputes and giving you a significant advantage.
  • Legal Advantage: Only federally registered trademarks can use the ® symbol, which enhances credibility and communicates legal protection. Unregistered marks can only use ™ (trademark) or ℠ (service mark), which carry less weight.
  • Sue Infringers: If you feel that another party is using an identical or similar version of your mark, you can file a lawsuit in federal court to stop infringement.
  • Sell It or Use It as Collateral: As trademarks are intellectual property assets, they can be sold, licensed, or used as collateral. Some entities choose to register their trademark not for the legal protection, but because it is an additional asset that they can sell, when they are looking to sell their company to a third party. A strong brand with legal protection can increase your company’s valuation and attractiveness to investors or buyers.
  • Keep Your Brand Consistent: Trademark protection helps maintain brand consistency. Consumers are more likely to trust brands with protected, recognizable marks.

In summary, registering a trademark with the USPTO is a powerful step toward building a secure, reputable, and scalable brand. It’s not just a legal safeguard; it’s a strategic and valuable business asset. 

Ready to secure your brand’s future? Contact Saunders Walsh & Beard today to learn more about protecting your intellectual property and unlocking the full potential of your business!


Read more

LLC vs Sole Proprietorship in Texas

Thinking of running your small business in your own name?


It’s common, but in Texas, forming an LLC or corporation offers big advantages.

When an individual starts their small business, they often do so in their own name. The thought process is typically that, as they are the only person involved with the business, there is no need to become a company or corporation. Not having employees or a payroll, some individuals think that the additional step of forming an entity is unnecessary and excessive. Some individuals do not believe they can form an entity when they are the only person involved with their business. What they may not know is that choosing not to operate as a sole proprietor in Texas and instead forming a Limited Liability Company (LLC), corporation, or other formal business entity can offer several key benefits.

1. Protect Your Personal Assets

With entities such as LLCs or corporations, owners are not personally liable for business debts, lawsuits, or obligations. Only the business assets are at risk. Inversely, sole proprietors (people who run businesses in their own personal names) are personally liable for all debts and legal actions against the business. Their personal assets (house, savings, etc.) could be at risk.

2. Boost Your Business Image

Additionally, by having “LLC” or “Inc.” in a business name may make the company appear more legitimate and professional, which can help when attracting investors, applying for business loans, and gaining client trust. While it might seem nominal, the suffix adds a measure of credibility and gravitas with potential clients and customers.

3. Enjoy Tax Flexibility

An individual who runs their business as a sole proprietorship has very few options when it comes to tax filings, whereas an entity allows for more versatility. An LLC can be taxed as a sole proprietorship, partnership, S corporation, or C corporation, depending on how an individual chooses to elect, providing the individual to optimize taxes based on their situation. There are multiple classifications of corporations. An S-corp enables pass-through taxation; avoids double taxation, while a C-corp has potential tax advantages on retained earnings but is subject to double taxation unless planned carefully. Inversely, a sole proprietor has no tax flexibility. All income is reported on their personal tax return (Schedule C), and they are subject to self-employment taxes on all profits.

4. Build a Stronger Business Foundation 

Formal entities provide a clear separation between personal and business finances as well as making it easier to build business credit and maintain legal protection.

An LLC or corporation can have multiple owners (members/shareholders) and is not tied to one person, making it easier to transfer ownership, bring on partners or investors, and continue operations if a member leaves or passes away. With a sole proprietor, the business ends with the owner and can be harder to transfer or sell.

Business entities such as LLCs or corporations provide for more formal structure with defined roles, governance, and rules (operating agreement, bylaws). Additionally, they can help prevent internal disputes and set clear expectations among owners or investors.

In sum, who Should Consider an LLC or Corporation?

  • Anyone worried about personal liability: Protect your assets!
  • Growing businesses: Hiring employees or seeking investment? Formalize your structure.
  • Businesses in “risky” industries: Healthcare, food services, consulting—consider the extra protection.
  • Those planning for the long-term: If you want to build a business that can continue beyond just you, an entity is crucial.

Don’t leave your future to chance. Contact us today to discuss forming an LLC or corporation in Texas.


Disclaimer: This blog post provides general information and not legal or tax advice. Consult with a legal and/or tax professional to determine the best entity type for your situation.


Read more

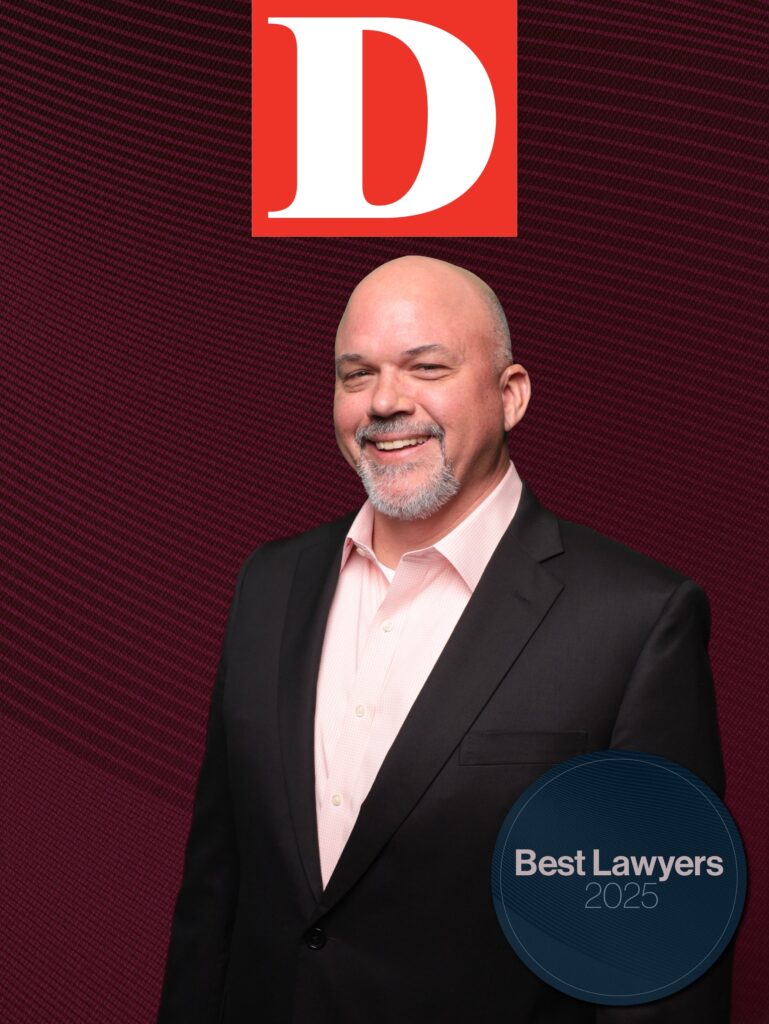
SWB's Jacob D. Thomas Named “Best of D” 2025 by D Magazine

Attorney Jacob Thomas named Best of D 2025Jacob D. Thomas, partner at Saunders, Walsh & Beard, is being honored as “Best of D” 2025 for Construction & Business Litigation by D Magazine. Board Certified in Construction Law by the Texas Board of Legal Specializations, Jacob represents owners, general contractors, subcontractors, engineers, and suppliers in a broad range of disputes arising from commercial and residential construction projects.
Mr. Thomas emphasizes preparedness and draws on his knowledge and experience to formulate an approach that focuses on achieving his client’s goals as efficiently and effectively as possible. From the start of the case until its resolution, Mr. Thomas communicates with his client and offers him or her appropriate and useful guidance to enable his client to make informed decisions.

As a mediator, Jacob resolves conflicts involving commercial construction, residential construction, partner/shareholder litigation, and general business disputes. Jacob is one of only a handful of mediators based in Collin County focusing solely on commercial litigation.

In recognition of his ethical standards and exceptional results, Mr. Thomas has an Avvo “Superb” rating and an AV rating from Martindale, Texas Super Lawyers Rising Star (2015-2018), and Texas Super Lawyer (2020-present).

If you are facing challenges in construction or business litigation, don’t navigate these complexities alone. Contact Jacob D. Thomas today and discover how his expertise can help you achieve your goals efficiently and effectively. Visit Saunders, Walsh & Beard or call us at 214-919-3555 to get started.

Read more

Corporate Transparency Act Compliance

Are You Prepared for the Corporate Transparency Act? Key Insights and Deadlines

The TL;DR of FinCEN BOIR: On December 27, 2024, the requirement of the FinCEN BOIR is on hold. Stay tuned.

UPDATE December 27, 2024, the U.S. Court of Appeals for the Fifth Circuit granted a stay of the district court’s preliminary injunction, meaning the Corporate Transparency Act (CTA) filing requirements have been reinstated and most filings will now be due January 13, 2025 instead of the December 31, 2024 prior deadline. However, a Fifth Circuit panel has reinstated a nationwide injunction blocking enforcement of the Corporate Transparency Act, three days after a different panel lifted it.

UPDATE December 26, 2024: On December 23, 2024, the U.S. Court of Appeals for the Fifth Circuit granted a stay of the district court’s preliminary injunction, meaning the Corporate Transparency Act (CTA) filing requirements have been reinstated and most filings will now be due January 13, 2025 instead of the December 31, 2024 prior deadline.

UPDATE December 3, 2024: In Texas Top Cop Shop v Garland et al. (case 4:24-cv-00478 December 3, 2024), the U.S. District Court for the Eastern District of Texas issued a nationwide preliminary injunction against the enforcement of the Corporate Transparency Act (CTA), questioning its constitutionality and its impact on small businesses. This means that if you have not yet completed the FinCEN Beneficial Ownership Information Report (“BOIR”), you do not need to do so at this time. However, please be aware that this ruling may be overturned in subsequent proceedings so be aware that while the requirement is suspended at this time, it may be revived in time to come.”


In 2021, Congress passed a new law affecting most businesses called the Corporate Transparency Act (CTA). Unfortunately, the majority of corporations and LLCs are unaware of this new regulation, which could lead to significant penalties as early as January 1, 2025.

The CTA’s purpose is to create business ownership transparency by identifying individuals who have either direct or indirect ownership (beneficial ownership) in a company. The overall goal is to alleviate fraudulent and illegal activities. The Financial Crimes Enforcement Network (FinCEN) began accepting Beneficial Ownership Information Reports (BOIR) through their website in January 2024.

States such as Delaware and Wyoming do not require corporations nor LLC’s to identify the owners of the entities, allowing for anonymity of said individuals. Congress views this as a potential threat to national security, as such secrecy could allow for foreign individuals or companies to acquire land or business interests that could potentially be against the interests of the nation or in violation of our laws.

Note that any information filed with FinCEN through a BOIR is not publicly available and the FinCEN database is private and for government use only. That being said, if you’ve created your entity in a state such as Texas, said information is public record through your filing with the Texas Secretary of State, as Texas requires entities to list all of its owners, regardless of their percentage.

Any reporting entity created or registered to do business before January 1, 2024, will have until January 1, 2025, to file its initial BOIR. If you created your entity in 2023 or 1983, you have until December 31, 2024, to file your BOIR.

Entities created or registered in 2024 have 90 days from their registration to file this information, and those created or registered after January 1, 2025, will have only 30 days to file. So, if you create a reporting entity, such as a for-profit corporation, in early December of 2024, you will have until early March of 2025. However, if you create a reporting entity in late January of 2025, you will also have until early March of 2025 to report.

A beneficial owner anyone who directly or indirectly exercises substantial control over or owns or controls at least 25% interest in a business.

To clarify, an individual exercises substantial control over a reporting company if they fall into any of the following categories: a) If the individual is a senior officer; b) if the individual has authority to appoint or remove certain officers or a majority of directors; c) if the individual is an important decision-maker; d) if the individual has any other form of substantial control, or; e) if an individual has 25% ownership of the entity, regardless of how much or how little control they have as to the operations and management of the reporting company.

An entity may need to report information about its beneficial owners if it is a corporation, a limited liability company, or was otherwise created in the United States by filing a document with a secretary of state or any similar office under the law of a state or Tribal jurisdiction; or if it is a foreign company registered to do business in any U.S. state or Tribal jurisdiction by such a filing.

Not all entities are deemed “reporting entities,” as they are required to state and/or federal regulations that require the reporting of beneficial ownership. These exempt entities include, but are not limited to accounting firms, banks, brokers/securities dealers, credit unions, governmental authorities, insurance companies, investments companies and advisors, public utilities, tax-exempt entities, and venture capital fund advisors. A good rule of thumb is that if your entity reports to a regulating agency, the odds are more likely that you could be exempt from the BOIR requirement. Saunders, Walsh & Beard recommends that you verify your entity is exempt before making any assumption.

When an entity is completing their BOIR, it is required to provide basic information for itself and all beneficial owners. The reporting entity must provide its legal name, trade names, address, jurisdiction of registration, and its taxpayer identification number. Beneficial owners must provide their name, date of birth, residential address, and an identifying number from an identification document such as a passport or driver’s license. As any entity from a multi-million-dollar corporation to a sole-owned LLC must file their BOIR, the information required by FinCEN is nothing complex or intricate, but it is still imperative that said information is filed by the deadline.

As a business owner, you might have received mailings from third parties charging $500 or more for them to file the BOIR on your behalf, but most BOIRs can be completed within 15 minutes by the business owner(s).

A failure to file may become extremely costly, with civil penalties starting at $500 per day and criminal penalties of up to $10,000 and/or two years in prison. You can file the BOIR online at https://www.fincen.gov/boi or mail in a hard copy of the report. Once the report is filed, it only needs to be updated if there is a change in ownership, or a change in any of the other information provided in the report, such as a change in the address of a beneficial owner.

While the government has not effectively informed the public of this new requirement and there is pending litigation stemming from such, we strongly encourage you to file before your entity’s deadline.

At Saunders, Walsh & Beard we are always happy to assist you with any of your business needs, governmental compliance, or otherwise. If you have any questions about this new requirement or if you have any other business issues, please do not hesitate to contact us to speak with one of our transactional law professionals.

Read more

USPTO Office Actions

Understanding Office Actions: A Guide for Trademark Applicants

Once you’ve applied for a trademark with the United States Patent and Trademark Office (“USPTO”), it will be months, if not longer, before you receive word that your application has been reviewed. So, when you receive notice from the USPTO that there’s an issue with your application, commonly known as an “Office Action,” it might seem disheartening, in all that waiting has been for naught.

An Office Action is an official letter from the USPTO Examining Attorney that states issues with your application that need to be addressed before your trademark can proceed to registration. If/when you receive an Office Action, here’s what you need to know and do.

1. Determine the Type of Office Action
There are two primary types of Office Actions: non-final and final.

  1. A non-final Office Action raises concerns or objections about your application that can still be corrected or addressed. You will most likely receive a non-final Office Action first, and you will have an opportunity to amend your application or address any concerns that the USPTO Examining Attorney has raised.
  2. A final Office Action means that the USPTO Examining Attorney was not satisfied with your responses to a prior non-final Office Action. Depending on the nature of the Office Action, you might receive multiple non-final Office Actions before the USPTO Examining Attorney sends the final Office Action. Once you receive a final Office Action, you will need to address all concerns raised by the USPTO Examining Attorney to their satisfaction, or risk a rejection of your application. That being said, if you do receive a final refusal from the USPTO, you do have the right to appeal to the Trademark Trial and Appeal Board.

2. Determine the Reasons for the Office Action
The Office Action will contain the reasons for the refusal in bullet point form, with each refusal being elaborated upon further down the letter.

  • Likelihood of Confusion: This will be where the USPTO Examining Attorney might feel that your mark is too similar to one that is already registered. Trademarks are marketing materials, and the purpose of registration is to protect one’s brand, so the USPTO is extremely conscious of a risk of confusion in the marketplace.
  • Descriptiveness: Your mark may be considered too descriptive of the goods or services offered. For example, if you made green shirts and you attempted to apply for the word mark of “The Green Shirt Company,” it would be refused as the name clearly states the product you sell. That being said, a company making green shirts that wanted to register the word mark “The Growling Tiger’s Shirt Company,” you’d have a better chance of success, so long as your shirts didn’t incorporate a growling tiger in the design.
  • Specimen Issues: At some point prior to your registration, you will need to provide a specimen that shows you are using your mark in commerce. The USPTO might determine that the specimen you’ve provided is insufficient for reasons such as you haven’t showed how the mark is being used in commerce or the mark does not align with your applied class(es).
  • Disclaimer Requirement: These Office Actions stem from the inclusion of a generic or descriptive portion within your mark. Going back to the example earlier, in an application for “The Growling Tiger’s Shirt Company,” the USPTO might require you to disclaim that you aren’t claiming exclusive ownership of the “Shirt Company” portion of the mark. As a whole, the mark is acceptable, but the USPTO wants to have you state that there are portions of the mark that are “public domain.” In a situation like this, the totality of the mark is more than a sum of its parts.
    Once you’ve ascertained what issues the USPTO has with your application, you can formulate a response to address the issues fully and swiftly.

3. Seek Legal Counsel
Some Office Actions might seem to be addressed easily enough, but experienced attorneys understand the nuances of particular Office Actions and might know of responses that could prevent additional Office Actions that stem from the initial response. You’ve spent a considerable amount of time and money in preparing your application, and you don’t want pride to jeopardize over a year’s worth of work and the associated costs.

4. Respond to the Office Action
If the Office Action is non-final, you must submit a response within three months of the issuance date. Note that until December 3, 2022, an applicant had six months to respond, from the issuance date. If you’ve had trademark experience in the past, it’s very important to note this distinction, because many individuals delay preparing a response, and this shortened deadline has caught some experienced business owners off-guard. An adequate response should:

  • Address each issue raised by the examiner with specific arguments or amendments.
  • If the issue is a likelihood of confusion, you may argue that your trademark is sufficiently different from the cited mark or that the goods and services are unrelated. Typically, in a situation such as this, using precedent of marks in similar positions is a good method in arguing your case for allowance.
  • If the USPTO claims the mark is too descriptive, you could argue that the mark has acquired distinctiveness in the marketplace or that it the mark is suggestive rather than descriptive. For example, Greyhound would be considered a suggestive mark, because it suggests swiftness, but does not speak to a bus line directly. Much like likelihood of confusion Office Actions, these responses are typically nuanced and can benefit from an experienced attorney.
  • For specimen rejections, you will need to submit a new specimen that better demonstrates the trademark in use. It could be a screenshot of a webpage or the packaging of the product.

5. Monitor Your File
The process of obtaining trademark registration requires attention to detail and deadlines. If you receive an Office Action, review it, ascertain what actions it requires, and plan your response. Additionally, you can always follow your trademark’s registration process through the USPTO’s Trademark Status and Document Retrieval system, that has the full history of all documents related to your filing, be it from the applicant or the USPTO. We recommend that you check any pending trademark bi-weekly, just to remain as informed as possible and avoid being blindsided by an upcoming due date.

If you’ve received an Office Action from the USPTO, don’t panic! Contact us today to help you navigate the response process and ensure your application stays on track for successful registration.

Read more

SWB Announces Texas Super Lawyers 2024

Saunders, Walsh & Beard proudly announces J. Brantley Saunders, Mark A. Walsh, Lewis L. Isaacks, Alexander N. Beard, and Jacob D. Thomas, as Texas Super Lawyers for 2024. Super Lawyers is a rating service of outstanding lawyers with high peer recognition and professional achievement. Attorneys are selected through a multi-phased process including independent research, peer nominations, and peer evaluations. Each year, no more than 5% of the lawyers in Texas are selected by the research team at Super Lawyers to receive this honor. To learn more, visit https://www.superlawyers.com/about/selection process.html.

Saunders, Walsh & Beard Announces Texas Super Lawyers 2025: Honoring J. Brantley Saunders, Mark A. Walsh, Lewis L. Isaacks, Alexander N. Beard, and Jacob D. Thomas
Saunders, Walsh & Beard Announces Texas Super Lawyers 2024: Honoring J. Brantley Saunders, Mark A. Walsh, Lewis L. Isaacks, Alexander N. Beard, and Jacob D. Thomas

Read more

Protecting Your Brand with a Trademark

With a business, branding is everything. From McDonald’s iconic “Golden Arches” to Nike’s catchphrase “Just do it!”, any savvy company is best served in protecting its intellectual property, and there’s no better way to protect your brand than to register a trademark with the United States Patent and Trademark Office (USPTO). Registering a trademark provides federal protection from infringement and entitles you to statutory damages. Trademarks can be images, names, or phrases, so long as they represent your business.


Getting Started

Since the application is a sunken cost that is non-refundable, regardless of whether the mark is approved, it is advisable to perform a search on the USPTO trademark search engine, to see what possible “competition” you might have for your mark. The link is here – Trademark Search Trademark Search (uspto.gov). The 45 International Classes cover any goods or services that a business might provide. It is advised to only be concerned with the International Class(es) that would apply to your mark. It’s why Dove Soap and Dove Ice Cream can co-exist. Trademarks exist to prevent consumer confusion, so ideally an individual wouldn’t take a bite out of a bar of soap, nor would they rub a chocolate-covered ice cream bar under their arms in the shower.

5 Levels of Distinction

Also, even if your mark is not found in the search engine, we will need to make sure that it has a certain level of distinctiveness. There are five levels of distinction for trademarks with the stronger the distinctiveness is, the more likely you’ll be approved for registration.

I. Fanciful

The highest level is “Fanciful.” This is a mark that has no relation whatsoever to the goods or services being offered and is also created solely to represent the good or service. Things like “Adidas” or “Xerox” are examples, as those words did not “exist” before the companies created them.

II. Arbitrary

The next level is “Arbitrary.” This mark is a word that has been known to the populace before the application/use of it as a mark, but it is wholly unrelated to the goods or services provided. Things like “Apple” or “Starbucks,” as if you’d never known of the computer company or the coffee chain, you’d be hard-pressed to assume what the companies do.

III. Suggestive

The third level is “Suggestive.” These marks suggest the product or service offered, without explicitly saying it. For example, even if you’d never heard of the chain, if I asked you if you wanted something from “Burger King,” you’d assume that it was a restaurant of some sort, probably selling hamburgers.

The next two levels are difficult, in terms of justifying federal protection.

IV. Descriptive

The “stronger” of the two is “Descriptive.” These marks describe the purpose, nature, or attribute of the product or service and are not considered to be eligible for registration. However, in exceptional circumstances, a descriptive mark could be registerable if it has acquired distinctiveness—through long-term usage in the eyes of consumers. When possible, you always want to argue that your mark is “Suggestive,” rather than “Descriptive,” and this is a common area where you’ll receive an office action from the USPTO, where they’ll claim it is the latter, and you’ll want to argue that the former applies.

V. Generic

Finally, the weakest mark is “Generic,” and it will never be protected, as it is too commonly used to have any distinctiveness. For example, I couldn’t trademark “Computer” or “Phone,” by themselves, as they are the names of the products they represent. (That being said, “iPhone” is a Suggestive mark, through the use of the letter “i” at the front of the name.) Also, a brand can be a victim of its success, in that it has come to dominate the market and as such, the brand name represents not just the particular product line, but the type of product in general. (Think of “Kleenex” being interchangeable with “facial tissue.”)

Even if you do get a refusal or opposition to the mark, once you’ve applied (an “Office Action”), you will have the ability to respond to that office action to state your case why their refusal is not well-reasoned, so know that you can always fight back against a refusal.

At some point in the application process, you must show that the mark is in use in commerce. If you have an idea for a slogan or a logo, but don’t have it currently used to represent your business, you can still file to register the trademark, but at some point, you will need to show that it is being used by your goods or services.

Give Us a Call

The experts at Saunders, Walsh & Beard are more than happy to assist you with any questions or needs in registering a trademark, renewing a trademark registration, or defending against an Office Action. The trademark process is a lengthy one, where applications submitted aren’t reviewed for ten months, as of 2023. You want to make sure you have a professional on your side to save you the time and stress of undergoing this process alone.

Read more

Matthew Duke Joins SWB's Transactional Business Practice

Saunders, Walsh & Beard welcomes associate Matthew Duke. Matt’s primary practice areas focus on transactional, real estate, and business law, as well as estate planning. With experience as in-house counsel, Matt has the insight to navigate the issues a company might face, ranging from formation to wind-down plans, as well as the day-to-day issues that occur in the interim. Read more about Matt here. Please join us in welcoming, Matthew!


Read more

Warning to Restoration Contractors and Roofers: The Old Way of Doing Business is Over.

On August 3, 2017, the 2nd District Court of Appeals in Fort Worth granted class certification against Lon Smith Roofing (LSRC), a prominent North Texas Roofer, for violation of the Texas Public Insurance Adjusting Act. Given the direction the courts in North Texas have gone in the past few years, the ruling is not a surprise. It is a warning to restoration contractors in general, and roofers in particular, that the old way of doing business is over. Contractors that negotiate with, or even represent themselves as able and willing to negotiate with, insurance adjusters do so at their own peril. (read more)

By way of background, in September 2013, the Keys sued LSRC asking the court to declare their contract void and to order the return – to them – of all monies their insurance company paid to the roofer. It’s important to remember that this is not a lawsuit about whether the roof was properly or timely installed. The roof doesn’t leak, the color isn’t wrong, the roofer didn’t damage the driveway or flower beds, or fail to respond to warranty claims. This lawsuit, which is a continuation of a dispute that started in 2011, is about language that, until recently, was commonly found in roofing contracts throughout the state of Texas.  Language that I still routinely see in roofing contracts today.

The Keys asked the 236th District Court in Tarrant County to approve them to act as representative plaintiffs in a class action lawsuit against LSRC. On October 15, 2015, the district court judge signed an order granting the class certification. That order was immediately appealed. Last week, after almost two years, the appellate court issued its ruling upholding the class certification on the Keys’ claim for the “return” of all monies paid to the roofer as part of their declaratory judgment claim (violation of Public Insurance Adjuster’s Statute/Insurance Code 4102) and the DTPA claim that provides for the potential for treble damages for violation of Texas Insurance Code 541 (unfair methods of competition and unfair or deceptive acts or practices). Class certification was denied for the DTPA claim for unconscionability.

The appellate court’s decision can, and likely will, be appealed to the Texas Supreme Court, who can choose to review that ruling, or to leave it undisturbed. In the meanwhile, the ruling upholding class certification is a further step in the continuum of cases favoring consumers to the detriment of restoration contractors. In discussing the facts supporting its decision to uphold the class certification, the court cited to testimony from Mr. Keys that the roofer “never told him that he could or should get a public insurance adjuster involved in his roof-damage claim under his homeowners’ policy” and that the homeowner “understood that [Roofer] was contracting to discuss his insurance claim with his insurer and was also contracting to repair his roof.“

Some groups are claiming this as a victory for consumers. Whatever your perspective on this issue, what is clear is that lawsuits claiming violations of the Public Insurance Adjuster (PIA) law have just been given a big boost via class certification.

What does mean for those of you working in the restoration contracting community? First, what happened to this roofer could have happened to any number of other roofers using the same or similar language in their contracts. Or any roofer negotiating claims with insurance adjusters. The ability to initiate class action lawsuits will embolden plaintiff’s attorneys to pursue similar claims against restoration contractors and roofers since they’ll only have to prove the representative plaintiff’s claim rather than the claims of every plaintiff taking part in the class action suit (one plaintiff – multiple verdicts). The cost to defend against a lawsuit of this type, win or lose, is extremely expensive. Further, if you lose, you not only have to write a check to the property owner for anything paid to you by them or their insurance company, sometimes tripled depending on whether the violation is determined to be knowing or intentional, you’ll also have to pay their legal fees, which will almost certainly greatly exceed the cost of the roof, to potentially every owner you sold for the last ten years (the span of the Keys/LSRC class action certification).

What should you do? Make sure your contract doesn’t contain any of the language the courts have determined violates the PIA statute. Include language in your contracts that specifically puts the owner on notice that you are not offering to and will not provide any PIA services. Don’t hold yourself out as an insurance expert. Understand and be ready to educate owners about their rights and options for dealing with insurance adjusters (attorney, appraisal, public insurance adjuster), making referrals where appropriate to ethical attorneys, appraisers, and public insurance adjusters who can advocate for the homeowner without taking away your sale. Restrict your conversations with insurance adjusters to answering questions regarding your scope and price – don’t negotiate the claim with the insurance adjuster.

Karen, you say, you don’t know what it’s like out in the real world. But I do understand, including that the majority of “negotiations” are initiated by the insurance adjuster. However, this PIA law isn’t going away. Instead, it is being vigorously and strictly enforced in the courts and by TDI, and the ramifications to your business cannot be ignored.

Read more

The Difference between a Rule of Interpretation and a Canon of Construction

One evening, sitting by the fireplace, sipping on a cup of hot coco, I found myself musing on the subject of contract interpretation.  I was pondering various active cases and my fading memory of my first year of law school when I had two revelations:  1) I am getting old, and 2) I had no idea if “construe against the grantor” was a rule or a canon.  I suspected that I was not the first attorney to have this particular question, so I became determined to find the answer and share it with you.

            I suspected that the two phrases were interchangeable.  It did not take much research to determine that most practicing attorneys think they are interchangeable, many appellate courts use the terms interchangeably, and the phrases are, in fact, NOT interchangeable.  The rules of contract interpretation are used to determine a contract’s meaning, to determine the parties’ respective rights and obligations, and to make the determination as to whether the contract is ambiguous.[1]  The canons of construction are utilized to resolve irreconcilable ambiguities in the words of a contract once the actual intent of the parties thereto proves indecipherable.[2]  In other words, if a contract is unambiguous, thus a question of law for the court’s determination, the court may utilize the rules of interpretation.  Should the contract prove to be ambiguous, the next step is to apply the canons of construction.

            If you are still a bit confused, I have compiled some examples for your reading pleasure:

Rules of Interpretation:

  1. Construe the agreement as a whole;
  2. Give each word and phrase its plain, grammatical meaning unless it definitely appears that such meaning would defeat the parties’ intent;
  3. Construe the agreement, if possible, so as to give each provision meaning and purpose so that no provision is rendered meaningless or moot;
  4. Express terms are favored over implied terms or subsequent conduct; and
  5. Surrounding circumstances may be considered – not to determine a party’s subjective intent – but to determine the appropriate meaning to ascribe to the language chosen by the parties.[3]

Canons of Construction:

  1. Ejusdem generis – when a general word or phrase follows a list of specifics, the general word or phrase will be interpreted to include only items of the same type as those listed;
  2. Expresio unius est exclusion alterus – to express or include one thing implies the exclusion of another;
  3. The specific governs over the general;
  4. The same words used in different parts of a writing have the same meaning;[4]
  5. Contra proferentum – Ambiguous contract terms are construed most strongly against the party responsible for drafting them; and
  6. Noscitur a sociis – The meaning of a word may be affected by its immediate context. Therefore, a court should construe or interpret a word in the context of the terms immediately preceding and following it.[5]

As you can see from my lists, if the phrase is in Latin, then it is likely a canon, not a rule.  I hope that you have found this helpful and that maybe it will allow you to enjoy your fireside coco in peace.  If you know of any additional rules or canons, or just some funny Latin phrases, please share them in the comment section below.

[1] Moon Royalty, LLC v. Boldrick Partners, 244 S.W.3d 391, 394-95 (Tex.App. – Eastland 2007, no pet.); McCarty v. Montgomery, 290 S.W.3d 525, 532 (Tex.App. – Eastland 2009, no pet.).

[2] Daniel B. Kostrub & Roger S. Christenson II, Canons of Construction for the Interpretation of Mineral Conveyances, Severances, Exceptions, and Reservations in Producing States (2013).

[3] On Parol: The Construction and Interpretation of Written Agreements and the Role of Extrinsic Evidence in Contract Litigation, 49 Baylor L.Rev. 657, 664–82 (1997).

[4] Vincent R. Martorana, A Guide to Contract Interpretation (2014).

[5] Keith A. Rowley, Contract Construction and Interpretation:  From the “Four Corners” to Parol Evidence (and Everything in Between), in Scholarly Works, Paper 554 (1999).

Read more

2015 is "in the books" -- is it in your corporate books?

corpKit

An out-of-date corporate book can cause unexpected legal problems!

It is important to keep your entity’s books up-to-date and to ensure compliance with the Texas Secretary of State’s Office and the Texas Comptroller’s Office.  Here are some common issues in need of updates:

  • Did your entity hold its required annual meeting and transcribe the minutes of that meeting?
  • Did your entity’s governing persons change during 2014-15?
  • Did ownership of the entity change during 2014-15?
  • Did your entity start transacting business in another state?
  • Did your entity start transacting business under a “DBA” or assumed name?
  • Did the registered agent information for your entity change?
  • Have additional shares or membership interests been issued?
  • Does your entity’s Company Agreement, Partnership Agreement, or Bylaws need to be updated to reflect changes or agreements between shareholders / partners / members?
  • Did you decide to terminate or wind up your entity?
  • If your entity experienced involuntary tax forfeiture, has your entity applied for reinstatement?

Other issues we assist clients with frequently are: lease renewals, real estate purchases, borrower financing representation, contract reviews, and collections.
Most of these updates take little time and can done very affordably.  Call anytime at (214) 919-3555.

Read more