A trusted business law firm in McKinney, TX.

Insurance

Insurance

What Your Insurance Agent Needs to Know When a Living Trust Owns a Texas Series LLC

What Your Insurance Agent Really Needs to Know When a Living Trust Owns a Texas Series LLC

When a Living Trust Owns a Texas Series LLC:

What Your Insurance Agent Really Needs to Know


When you combine a living trust, a Texas series LLC, and multiple lines of business insurance, you create a structure that is great for asset protection but confusing for insurance underwriting. This post walks through the key issues that come up when an insurance agent calls to “understand the disregarded entity tax structure” and how you, as counsel or advisor, can be ready with clear, consistent answers.

  1. Who Really Owns and Controls the Business?

The first thing a business‑insurance agent wants to nail down is: who is the insured risk?

In a typical planning structure:

  • The revocable living trust is the sole member of the parent LLC.
  • That parent LLC establishes multiple series, each holding a specific asset pool or business line (for example, separate rental properties or operating ventures).
  • The trustee—often the grantor—is the manager of the LLC and its series.

From an insurance standpoint, the key is to make sure:

  • The parent LLC and the relevant series appear as named insureds or scheduled entities on the policy.
  • The trust and the individual trustee/grantor appear as additional insureds (or co‑named insureds where possible).

This alignment reduces the risk that a claim is denied because the “real party” with liability or ownership was never properly named on the policy.

  1. Disregarded Entities: Tax Fiction vs. Insurance Reality

For federal tax purposes, single‑member LLCs (including those owned by a grantor trust) are routinely treated as disregarded entities. In practice, that means:

  • Each series’ income flows through the trust and onto the grantor’s Form 1040.
  • The IRS looks through the LLC and trust and taxes the grantor directly.

Insurance carriers, however, do not underwrite tax fictions. They care about:

  • Which legal entity holds title to the property or employs people.
  • Where operations occur and who signs contracts and leases.
  • Whose financial statements (often the grantor’s return plus entity‑level books) reflect the risk they are insuring.

The smart move is to explain to the agent that the tax treatment doesn’t change who owns assets or runs the business; it simply affects how income is reported. Then offer:

  • EINs for each series and the parent LLC.
  • A short explanation of how the grantor trust and disregarded entities report on the individual return.

This lets underwriting connect the dots between entity‑level exposures and the individual’s tax return they’ll often see in underwriting.

  1. How Texas Series LLCs Affect Coverage Design

Texas series LLCs are popular for real estate and multi‑asset businesses because each series can hold its own assets and liabilities while sitting under a single umbrella LLC. For insurance, this raises several design questions:

  • Should each series be treated as a separate “location” under one master policy, or as separate insured entities?
  • Should there be one combined program (with clear scheduling of each series) or separate policies for each series?
  • How should limits and umbrellas be structured to respect internal liability segregation while still providing practical coverage?

A common, practical approach:

  • Use one coordinated program, with the parent LLC and each active series listed by name.
  • Clearly schedule properties and operations under the correct series on the declarations and schedules.
  • If certain series have meaningfully different risk profiles (e.g., high‑risk operations vs. passive real estate), consider separate policies or endorsements to avoid cross‑subsidization of risk.

The better you document which series owns what, the easier it is for the agent to avoid gaps.

  1. Trust Ownership: Why It Matters to the Carrier

Trust ownership introduces two issues carriers care about: control and continuity.

With a revocable living trust:

  • The grantor and the trust are economically the same person during the grantor’s life.
  • However, the trust instrument governs what happens on incapacity or death—when a successor trustee steps in, and how business interests transition.

Insurance implications include:

  • Ensuring the trust itself is recognized on the policy, so coverage continues seamlessly even if the grantor dies or becomes incapacitated.
  • Ensuring the trustee (and any successor trustee) is recognized as having authority to act for the insured entities.
  • Clarifying that any change in trusteeship or substantial amendment to the trust will trigger notice to the agent so the carrier can update the policy if needed.

When you proactively share a high‑level summary of the trust’s role—without revealing unnecessary private details—you reduce carrier anxiety about “mystery owners” behind the scenes.

  1. Business Income, Payroll, and “Who Is the Employer?”

When agents ask about “the disregarded entity tax structure,” they are often really asking about:

  • Whose income is at risk for business‑income and extra‑expense coverage.
  • Who is the employer for workers’ comp, employment‑practices, and related coverages.

In a common arrangement:

  • The payroll for each line of business runs through the specific series’ EIN, even though the series is disregarded for income‑tax purposes.
  • The books and records track revenue, expenses, and payroll by series, then roll up through the parent LLC and ultimately to the grantor’s return.

For underwriting clarity, it helps to be ready with:

  • Current payroll reports by entity/series.
  • A brief explanation of where business‑income coverage should respond (e.g., at the series level, based on its own revenue).
  • Confirmation that the tax “flow‑through” does not change which entity is responsible for payroll taxes and employment obligations.

This makes it easier to size limits and price the policy correctly.

  1. Documentation and Communication Best Practices

To make these calls productive and avoid follow‑up confusion, it’s worth investing in a simple documentation package:

  • A one‑page structure diagram showing the trust, the parent LLC, and each series with a short label (e.g., “Series A – Elm St. Rental,” “Series B – Equipment Leasing”).
  • A brief written summary (1–2 paragraphs) explaining:
    • That the trust is a revocable grantor trust.
    • That each series is a single‑member LLC owned by the trust and treated as a disregarded entity.
    • That all income flows to the grantor’s Form 1040, but assets and operations are legally held at the entity/series level.
  • A list of requested policy positions, such as:
    • Parent LLC and each series as named insureds or scheduled entities.
    • Trust and trustee as additional insureds.
    • Agreement to notify the agent on changes to trustees, series, or major operations.

Having this ready before the call lets you answer the agent’s questions consistently and gives the underwriter something concrete to work from.

  1. How to Talk About “Disregarded” Without Losing the Agent

Finally, remember that “disregarded entity” is tax jargon. In conversations with agents:

  • Emphasize that for legal liability, each LLC series still exists and owns assets or runs operations.
  • Clarify that for tax reporting, those entities are ignored and everything flows to the individual grantor’s return.
  • Tie every explanation back to what the carrier cares about: who owns the property, who operates the business, who employs people, and whose financials demonstrate the risk.

If you keep the focus on legal ownership, operations, and claims exposure, the tax‑classification piece becomes a simple background detail rather than a point of confusion.
Michael A. Weaver


Prepare Your Documentation Package Today

Don’t wait for the call from the underwriter. Proactively assemble the documentation package described in Section 6—including your structure diagram, high-level trust summary, and desired policy positions—to ensure a smooth, confusion-free underwriting process and avoid gaps in coverage. Need help? Contact Mr. Mike Weaver, Partner at Saunders | Walsh, today.  
Read more

Texas Supreme Court Provides New Procedure for Pursuing UIM Claims Under Auto Policies

Texas Supreme Court ruling on UIM by SWB


Last Friday, the Texas Supreme Court issued a decision that will substantially impact how underinsured motorist (UIM) claims will now be litigated in Texas.  In Allstate Ins. Co. v. Irwin, Case No. 19-0885, a sharply divided court (5-4) held that an insurance carrier’s liability for UIM benefits may now be established in a declaratory judgment action.  The Court’s ruling signals a departure from the traditional manner in which these claims have typically been litigated, and will likely have a drastic impact on how they are litigated in the future.

In Brainard v. Trinity Universal Ins. Co., 216 S.W.3d 809 (Tex. 2006), the Court held that an insurance carrier has no legal obligation to pay UIM benefits until the insured obtains a judgment establishing the liability and underinsured status of the other motorist.  These are conditions precedent to recovery of contractual UIM benefits.  Until those determinations are made, the Court explained, “no contractual duty to pay” arises and “no just amount [is] owed.”  Id.  at 818.  Simply put, there can be no breach of the policy until these conditions have been satisfied.

In Allstate v. Irwin, the Court gave plaintiff attorneys a new procedural remedy for having UIM   claims decided.  Noting that UIM claims are contractual in nature, the Court held that the Declaratory Judgment Act can be used to determine the prerequisites for, and existence of, a valid UIM claim.  The Court reasoned that the issues to be decided were about coverage, rather than breach of the policy contract, and thus were proper subjects for declaratory relief.

The Court’s decision in Allstate v. Irwin signals a sea change in how UIM claims will likely now be litigated in Texas.  One major impact that the Court’s decision will have is on the recovery of attorneys’ fees.  In a typical breach of contract action, recovery of attorneys’ fees is not authorized unless there has been a breach of the contract.  Therefore, in a UIM context, those fees ordinarily would not be recoverable until there has been a refusal by the carrier to pay UIM benefits after liability and damages have been established.  Under the Declaratory Judgment Act, however, fees are discretionary with the court, but are typically awarded to the prevailing party.  Consequently, counsel representing claimants in these cases will likely be able to recover their fees before there has even been a breach or refusal by the carrier to pay policy benefits.  The potential ability to recover fees before there has been a breach will no doubt be the driving force behind the initiation of new UIM suits under the Declaratory Judgment Act.


Alex Beard has 30 years of experience representing individuals and businesses, with a practice focusing on liability insurance coverage, property damage insurance, and civil appeals. He has extensive experience with liability insurance claims, and enjoys analyzing coverage issues under numerous types of insurance, including commercial general liability, commercial auto and life. Read more about Alex and his insurance-related practice here: https://saunderswalsh.com/insurance-related-disputes/.

Read more

McKinney Tea Shop Takes COVID Insurance Battle to Fifth Circuit


Alex Beard argues case in Fifth Circuit

One of the hottest insurance issues stemming from the COVID pandemic is whether business interruption losses resulting from governmental shut-down orders are covered under standard commercial property insurance policies. Under most policies, the issue boils down to whether the shutdown of the business constitutes “direct physical loss of or damage to the property” so as to be covered. Courts across the country continue to grapple with this issue, primarily because the typical policy does not include definitions for the words “direct,” “physical,” and “loss,” leaving the meaning of those words (and thus the scope of coverage) unclear.

One of my clients, Aggie Investments, LLC, operates a small spice and tea shop located in downtown McKinney. The shop, Spice and Tea Merchants of McKinney, was forced to close its doors for a brief period last year in response to the Mayor of McKinney’s “shelter in place” order. The tea shop submitted a claim for its losses to its property insurer, and the insurance company promptly denied the claim, contending there was no “physical loss of or damage to” the property.

As a result of the denial of coverage, my client was forced to file a lawsuit against the insurer in Aggie Investments, LLC v. Continental Casualty Company, Case No. 4:21-cv-0013, in the United States District Court for the Eastern District of Texas, Sherman Division. The insurer then filed a motion to dismiss the case on the basis that no coverage was afforded by the tea shop’s policy. In ruling on the motion, U.S. District Judge Amos Mazzant followed what he believed to be mandatory authority from the Fifth Circuit. In this connection, he stated that “the Policy’s provisions require demonstrable harm to property to trigger coverage.” Applying this standard, he concluded that the tea shop did not sustain “direct physical loss” of the property, and dismissed the tea shop’s case.

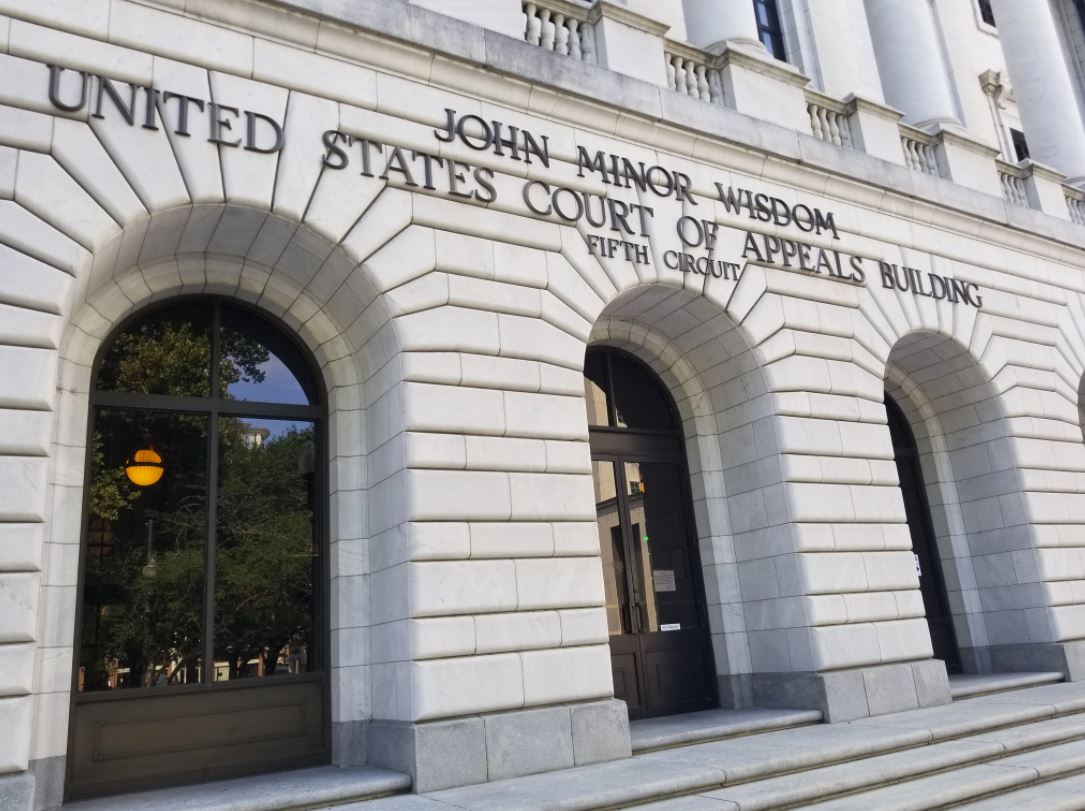
We believe that Justice Mazzant’s decision is in error, and is contrary to well-recognized Texas principles of contract interpretation. We also believe that the Fifth Circuit “authority” he and other Texas federal judges have relied upon in dismissing similar COVID coverage cases is flawed and does not accurately reflect Texas law. Therefore, earlier this week my client filed its notice of appeal to the U.S. Fifth Circuit Court of Appeals.

This will likely be the first case in which the Fifth Circuit squarely addresses this issue, so stay tuned for updates.


Alex Beard has 30 years of experience representing individuals and businesses, with a practice focusing on liability insurance coverage, property damage insurance, and civil appeals. He has extensive experience with liability insurance claims, and enjoys analyzing coverage issues under numerous types of insurance, including commercial general liability, commercial auto and life. Read more about Alex and his insurance-related practice here: https://saunderswalsh.com/insurance-related-disputes/.

Read more

Commercial Insurance Attorneys

The Insurance Council of Texas categorized the recent winter storm as the “largest insurance claim event in history.” At Saunders, Walsh & Beard, our insurance attorneys help businesses whose insurers have failed to perform their duties under their related policies. Therefore, if you do not receive the coverage you expect, you have options. Our insurance attorneys assist clients (large and small) to get the insurance coverage they paid for when they purchased their policy. If your company has a property damage claim your insurance company refuses to pay (or is making a “lowball” offer on) and you disagree with their decision/evaluation, then we can help. Our firm’s insurance coverage lawyers enjoy helping our clients in getting their property damage claims paid. We welcome the opportunity to discuss your case or situation. Call us today and schedule a time when we can discuss your insurance-related issue or dispute.

Insurance Coverage Claim Help at Saunders, Walsh & Beard

Mr. Alexander N. Beard & Mr. Mark D. Johnson focus their practice primarily on insurance coverage issues and related litigation. Their successful track record in these endeavors brings a great deal of recognition from fellow attorneys, including an AV Preeminent* peer review rating through Martindale-Hubbell and a “Superb” peer review rating through Avvo. You can learn more about their practice here.

Read more

Saunders, Walsh & Beard Coronavirus Insurance Recovery Team

Saunders, Walsh & Beard Coronavirus Insurance Recovery Team

Most business-interruption coverage includes losses from physical damage caused by hurricanes, fires, winds or theft—not a virus. Lawmakers have recently urged insurers to provide business interruption coverage under existing commercial property policies for companies’ losses due to closures tied to the novel coronavirus (COVID-19). These initial legislative efforts mark a good first step in trying to address companies’ business interruption coverage needs as the coronavirus crisis unfolds, but these matters are complex and will dictate the ultimate survival of countless businesses.

At Saunders Walsh & Beard, we help our clients (large and small) get the insurance coverage they paid for when they purchased their insurance policy. Two of our partners–Alex Beard and Mark Johnson–each have decades of experience dealing with insurance companies and analyzing insurance policies.

If your business has insurance coverage, but has been denied coverage for economic losses caused by government shutdowns over coronavirus, we welcome the opportunity to discuss your particular case or situation. We provide a free, initial review of your company’s insurance policy to assess the coverage that is afforded. If your company’s insurance claim has already been denied, we will analyze the insurance company’s position, determine whether it is correct, and advise you of your company’s rights.

Call us today and schedule a time when we can discuss your particular insurance-related issue or dispute.

Read more

“Dinosaur” Lawyers Successfully Obtain Dinosaur Insurance Recovery

Congratulations to Saunders, Walsh & Beard’s client, The Dinosaur Company (a division of Billings Productions), for obtaining full insurance benefits for the loss of 21 of its dinosaur replicas in North Carolina due to Hurricane Florence. The insurer for the Dinosaur Company initially filed the claim for the loss, and SWB’s own “dinosaur” lawyers, Alex Beard and Mark Johnson, stepped in to make sure Billings received all the insurance benefits it was entitled to under its insurance policy. Mr. Beard & Mr. Johnson convinced the insurance company its initial decision to pay only a portion of the loss was incorrect and, as a result, the Dinosaur Company received over a half a million dollars in additional policy benefits–all without having to file a lawsuit.

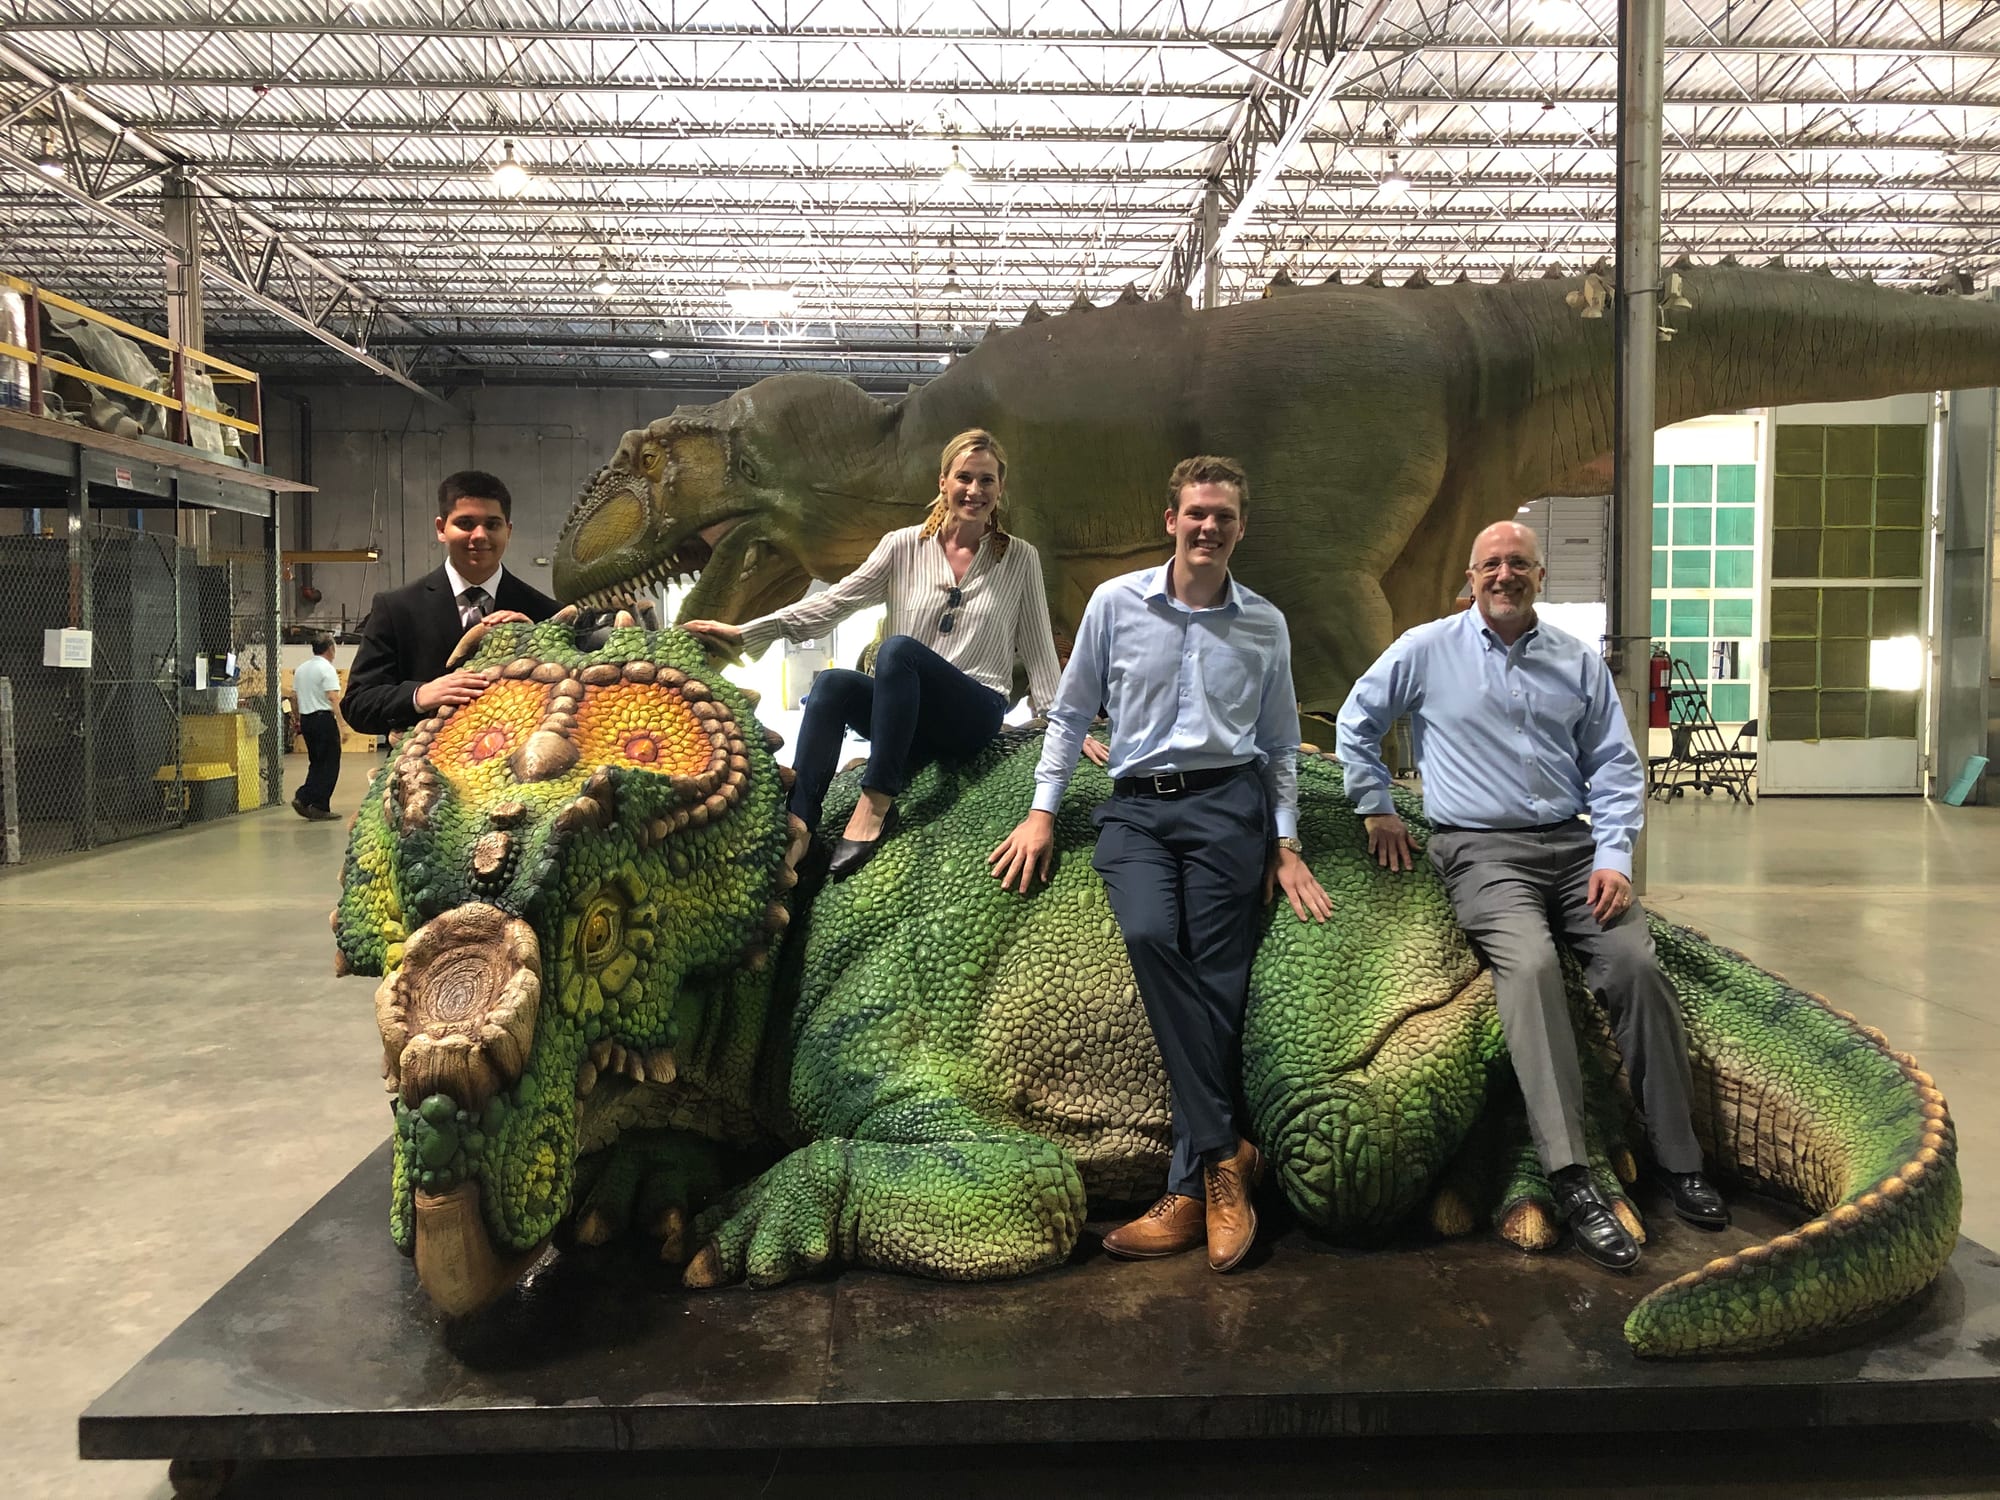
Mr. Beard (far right) at Billings Productions on June 28, 2019, with SWB Summer Interns and Associate Attorney, Haley Heinrich

At SWB, we help our clients (large and small) get the insurance coverage they paid for when they purchased their insurance policy. Two of our partners–Alex Beard and Mark Johnson–each have decades of experience dealing with insurance companies and analyzing insurance policies. In fact, both Mr. Beard and Mr. Johnson both represented insurance companies exclusively for several years, and they now leverage that valuable experience in representing our policyholder clients and assisting them with their insurance-related issues. You can read more about our Insurance-Related Dispute practice here: https://saunderswalsh.com/insurance-related-disputes/.

Call us today and schedule a time when we can discuss your particular insurance-related issue or dispute.


Read more

Warning to Restoration Contractors and Roofers: The Old Way of Doing Business is Over.

On August 3, 2017, the 2nd District Court of Appeals in Fort Worth granted class certification against Lon Smith Roofing (LSRC), a prominent North Texas Roofer, for violation of the Texas Public Insurance Adjusting Act. Given the direction the courts in North Texas have gone in the past few years, the ruling is not a surprise. It is a warning to restoration contractors in general, and roofers in particular, that the old way of doing business is over. Contractors that negotiate with, or even represent themselves as able and willing to negotiate with, insurance adjusters do so at their own peril. (read more)

By way of background, in September 2013, the Keys sued LSRC asking the court to declare their contract void and to order the return – to them – of all monies their insurance company paid to the roofer. It’s important to remember that this is not a lawsuit about whether the roof was properly or timely installed. The roof doesn’t leak, the color isn’t wrong, the roofer didn’t damage the driveway or flower beds, or fail to respond to warranty claims. This lawsuit, which is a continuation of a dispute that started in 2011, is about language that, until recently, was commonly found in roofing contracts throughout the state of Texas.  Language that I still routinely see in roofing contracts today.

The Keys asked the 236th District Court in Tarrant County to approve them to act as representative plaintiffs in a class action lawsuit against LSRC. On October 15, 2015, the district court judge signed an order granting the class certification. That order was immediately appealed. Last week, after almost two years, the appellate court issued its ruling upholding the class certification on the Keys’ claim for the “return” of all monies paid to the roofer as part of their declaratory judgment claim (violation of Public Insurance Adjuster’s Statute/Insurance Code 4102) and the DTPA claim that provides for the potential for treble damages for violation of Texas Insurance Code 541 (unfair methods of competition and unfair or deceptive acts or practices). Class certification was denied for the DTPA claim for unconscionability.

The appellate court’s decision can, and likely will, be appealed to the Texas Supreme Court, who can choose to review that ruling, or to leave it undisturbed. In the meanwhile, the ruling upholding class certification is a further step in the continuum of cases favoring consumers to the detriment of restoration contractors. In discussing the facts supporting its decision to uphold the class certification, the court cited to testimony from Mr. Keys that the roofer “never told him that he could or should get a public insurance adjuster involved in his roof-damage claim under his homeowners’ policy” and that the homeowner “understood that [Roofer] was contracting to discuss his insurance claim with his insurer and was also contracting to repair his roof.“

Some groups are claiming this as a victory for consumers. Whatever your perspective on this issue, what is clear is that lawsuits claiming violations of the Public Insurance Adjuster (PIA) law have just been given a big boost via class certification.

What does mean for those of you working in the restoration contracting community? First, what happened to this roofer could have happened to any number of other roofers using the same or similar language in their contracts. Or any roofer negotiating claims with insurance adjusters. The ability to initiate class action lawsuits will embolden plaintiff’s attorneys to pursue similar claims against restoration contractors and roofers since they’ll only have to prove the representative plaintiff’s claim rather than the claims of every plaintiff taking part in the class action suit (one plaintiff – multiple verdicts). The cost to defend against a lawsuit of this type, win or lose, is extremely expensive. Further, if you lose, you not only have to write a check to the property owner for anything paid to you by them or their insurance company, sometimes tripled depending on whether the violation is determined to be knowing or intentional, you’ll also have to pay their legal fees, which will almost certainly greatly exceed the cost of the roof, to potentially every owner you sold for the last ten years (the span of the Keys/LSRC class action certification).

What should you do? Make sure your contract doesn’t contain any of the language the courts have determined violates the PIA statute. Include language in your contracts that specifically puts the owner on notice that you are not offering to and will not provide any PIA services. Don’t hold yourself out as an insurance expert. Understand and be ready to educate owners about their rights and options for dealing with insurance adjusters (attorney, appraisal, public insurance adjuster), making referrals where appropriate to ethical attorneys, appraisers, and public insurance adjusters who can advocate for the homeowner without taking away your sale. Restrict your conversations with insurance adjusters to answering questions regarding your scope and price – don’t negotiate the claim with the insurance adjuster.

Karen, you say, you don’t know what it’s like out in the real world. But I do understand, including that the majority of “negotiations” are initiated by the insurance adjuster. However, this PIA law isn’t going away. Instead, it is being vigorously and strictly enforced in the courts and by TDI, and the ramifications to your business cannot be ignored.

Read more

SWB Wins Insurance Coverage for Clients in Federal Court

insurance-policy-and-gavel

Congratulations to our firm’s clients, Phil and Susan Swartztrauber, for winning a court order obtaining insurance coverage against Travelers Casualty and Surety Company of America.

The case was handled by Alex Beard.  The Swartztraubers were board members of their Home Owners Association (HOA), and were sued for alleged defamation in an underlying suit filed by the HOA’s President.  Travelers insured the HOA, but refused to provide the Swartztraubers with a defense to the defamation suit.

U.S. District Judge David Hittner disagreed, and ruled that Travelers breached its policy contract, and violated the Texas Prompt Payment Statute, by failing to provide the Swartztraubers with a defense.  So, Travelers will have to pay for the defense, legal fees and costs of the coverage case, as well as the underlying lawsuit.

Great work, Alex!


Read more

Decoding Chapter 140 of the CPRC

Subrogation

Chapter 140 of the Texas Civil Practice & Remedies Code is intended to limit the subrogation rights of an injured person’s health insurance provider.  When this statute was first enacted in 2014, an esteemed personal injury attorney told me that the new law was simple, “Everyone gets a third of the gross settlement.  The insurance company gets a third, the attorney gets a third, and the client gets a third.”  That certainly sounded simple enough.  It was a couple of months later, when applying the new statute to one of my cases, that I realized it was not that simple.  In fact, the “simple” explanation only caused me to question my own analysis of the law.

            After reading Chapter 140 a dozen times and reading a handful of blogs, articles, and CLE papers, I finally realized that all of the commentators were assuming that the plaintiff’s attorney took the case on a 30% contingency.  While that is a safe assumption, Chapter 140 does not actually limit an attorney’s contingency fee to 30%.

You can review the actual wording of Chapter 140 HERE, but allow me to restate the basics in plain language:

Applicability of Chapter:

  1. Plaintiff is injured by Defendant.
  2. Plaintiff is insured by an insurance company described in the statute (there are exceptions).
  3. Insurance pays for healthcare resulting from injury.
  4. Insurance company has subrogation rights.
  5. Plaintiff obtains a recovery from Defendant (i.e., the case settles).

Calculating Insurance Company’s Portion:

  1. When Plaintiff is not represented by an attorney:
    1. Insurance company gets lesser of:
      1. 1/2 gross recovery; or
      2. Total cost of benefits paid
    2. When Plaintiff is represented by an attorney:
      1. Insurance company gets lesser of:
        1. 1/2 gross recovery, minus 1/3 of Insurance Company’s share for the attorney and minus legal expenses; or
        2. Total cost of benefits paid, minus 1/3 of Insurance Company’s share for the attorney and minus legal expenses

As stated previously, these are just the basics; there is a lot more in the statute.  However, this explanation is intended to get past the overly simplistic 1/3, 1/3, 1/3 explanation that was previously given to me.

Let’s apply this explanation to an example:

Paul Plaintiff is injured by Dan Defendant.  Paul’s insurance company pays $50,000 for his healthcare resulting from the injury and asserts its right to subrogation under Paul’s policy.  Paul hires an attorney.  Paul agrees to pay his attorney 40% of his gross recovery plus expenses.  Paul’s attorney settles Paul’s claim against Dan for $90,000.

If my friend were correct, everyone would get $30,000.  The insurance company would have to eat $20,000, and Paul’s attorney would eat $6,000 plus his expenses (let’s say $1,000).  That is incorrect.

According to the statute, the math should look like this:

Insurance company’s portion starts at 1/2 the gross recovery ($45,000).  It is then reduced by a 1/3 ($15,000), and is further reduced by Paul’s legal expenses ($1,000):  $45,000 – $15,000 – $1,000 = $29,000.  The insurance company gets $29,000 and is going to write of $21,000.

Paul’s attorney is going to get 40% of the gross recovery ($36,000), plus his expenses ($1,000), for a total of $37,000.

Paul gets $24,000.

While Paul gets less than everyone else, he is still better off than he would have been under common law, which required the insurance company be made whole.  Under the common law, Paul would have received $3,000 ($90,000 – $50,000 – $37,000 = $3,000).

What does this mean for the practicing attorney?  I think it makes smaller personal injury cases more attractive and easier to settle.  If Paul would have been forced to pay his insurance company $50,000 of the proceeds, Paul’s attorney could never have settled his case for $90,000.  As a result of Chapter 140, Paul and his attorney are happy campers and Dan Defendant’s insurance carrier is also quite pleased.

If you see a flaw in my reasoning or my math, or if you would simply like to share your thoughts, please leave a comment below.

Read more

Does a Policyholder Have a Right to Select Independent Counsel To Represent It When the Insurance Company Reserves Its Rights?

Dear Insured

Most liability insurance policies – whether they be commercial general liability, business owners, errors and omissions, homeowners or auto – require the insurance company to defend the policyholder against lawsuits where the plaintiff is seeking damages potentially covered by the insurance policy.

When the lawsuit gets filed, and the policyholder is served with suit papers, the policyholder is required to tender those suit papers to the insurance company and request a defense if it desires one.  When the insurance company receives such a request, it will often agree to provide the policyholder with a defense to the lawsuit through the attorney it hires (often referred to as panel counsel) while at the same time “reserving its rights.”  The insurance company can reserve its rights for a number of reasons, but it is usually because the insurance company has determined that one or more of the claims asserted in the lawsuit may not be covered by the insurance policy.  What the insurance company is actually doing is preserving its right to ultimately deny any responsibility to pay any judgment or settlement for damages that are not covered by the policy.

      As a lawyer who has practiced in the insurance arena for many years, I am often asked by policyholders whether they are required to accept the panel counsel offered by the insurance company that is reserving its rights. The answer I give is one that you will often hear lawyers give in a variety of circumstances:  it depends.  You see, when an insurer provides a defense under a reservation of rights, it creates a potential conflict of interest.  The potential conflict arises from the fact that the attorney hired to defend the policyholder owes an unqualified duty of loyalty to the policyholder, yet is getting his fees paid by the insurance company.  Consequently, the existence of this potential conflict will sometimes prevent the insurance company from providing a defense through its panel counsel and will give the policyholder the right to select its own attorney to defend it in the lawsuit, with the insurance company to pick up the tab.

            The Texas Supreme Court explained when such a right arises in a case called Northern County Mutual Ins. Co. v. Davalos, 140 S.W.3d 685 (Tex. 2004):

In the typical coverage dispute, an insurer will issue a reservation of rights letter, which creates a potential conflict of interest. And when the facts to be adjudicated in the liability lawsuit are the same facts upon which coverage depends, the conflict of interest will prevent the insurer from conducting the defense.

            In a subsequent case, the U.S. 5th Circuit Court of Appeals clarified what it believed the Supreme Court meant when it used the words “facts to be adjudicated.”  See Downhole Navigator, LLC v. Nautilus Ins. Co., 686 F.3d 325 (5th Cir. 2012). The Court held that the term “adjudicate” plainly means “to rule upon judicially.”  Accordingly,  a policyholder will have the right to select independent counsel to represent it in a lawsuit – at the insurance company’s expense – when the court or jury in the underlying suit will be required to decide the same facts upon which coverage depends.

            When might this occur? The court in Downhole Navigator provided a few examples. One is where the lawsuit alleges intentional wrongdoing and the policy contains an exclusion for intentional conduct.  Another example is where the underlying lawsuit raises a claim for breach of contract, and the insurer reserves the right to deny coverage based upon a breach of contact exclusion in the policy. Yet another example is where the insurer reserves the right deny coverage for damages taking place outside the contract period and the underlying lawsuit involves the issue of when damages took place. These were just some of the examples provided by the court in Downhill Navigator; there obviously may be others depending on the terms of the particular policy at issue and the factual allegations of the particular lawsuit.

            The right to select independent counsel can be a valuable right, especially when the policyholder already has competent counsel which it knows and trusts.  Therefore, whenever a policyholder is sued and the insurance company offers a defense to the lawsuit under a reservation of rights, it behooves the policyholder to carefully analyze whether it might be entitled to select independent counsel to represent it due to the existence of the potential conflict.  Case law in this area demonstrates that it is not always easy to determine whether the same facts to be adjudicated in the liability suit are the same facts upon which coverage hinges.  Consequently, it is always best to have an attorney well-versed in insurance matters conduct this analysis.

Read more

Insurance for Legal Marijuana-Related Businesses: A Budding New Industry

farmers-insurance-marijuana-collectives-retail-outlets-300x300My grandmother was always fond of saying “The whole world is going to pot.”  Little did she know how prophetic those words might be someday.

Several states have now legalized the recreational use of marijuana, and more states are likely to join the party in years to come.  This has already given rise to a frenzy of business activity calculated to take advantage of this growing trend.  One market study conducted several years ago estimated that the U.S national legal marijuana market was valued at $ 1.53 billion.  That number was projected to increase by 68 percent to 2.57 billion this year.

Regardless of where you stand on the issue of legalized marijuana, you can’t deny the numbers.  They don’t lie.  Marijuana, for better or worse, is truly a “growth” industry.  As a result of the growing trend, whole industry sectors are rising, and new businesses are sprouting every day.  One of those industries is insurance.  For whatever reason, the insurance industry often lags behind the other industries which it serves.  Cannabusinesses are no exception.

To be sure, the players involved in the marijuana supply chain, whether they be growers, distributors, or retailers, have all sorts of insurance needs.  Traditional forms of insurance like property damage, theft, and liability are still needed, but the list does not end there.  Unique and special risks are often associated with many of these “420” businesses, and a lot of those risks stem from the fact that marijuana is still considered an illegal drug under federal law.  Nevertheless, companies devoted to serving the specific needs of the cannabis industry, like Cannasure, are beginning to crop up to meet those needs.  It’s high time they did.

Written By: Alex Beard

Read more